Real estate investing rewards conviction, but durable returns come from discipline. In strong markets, it is easy to confuse rising values and full occupancy with sound risk management. A portfolio can look healthy right up until vacancies increase, debt costs reset higher, insurance exclusions become expensive surprises, or a single local market weakens faster than expected. That is why portfolio protection deserves the same attention as acquisition strategy.
Table Of Content
- Why portfolio protection matters more in the current market
- Strategy 1: Diversify beyond property count
- What diversification looks like in practice
- A practical diversification checklist
- Strategy 2: Treat insurance and hazard planning as core infrastructure
- What to review in your insurance program
- Insurance should support portfolio strategy
- Strategy 3: Use conservative leverage and stress test every asset
- Key leverage metrics that matter
- A simple stress testing approach
- Strategy 4: Protect cash flow through disciplined asset management
- Operational habits that reduce portfolio risk
- Management should reflect tenant demand, not owner preference
- Strategy 5: Keep liquidity and scenario plans for the unexpected
- What a practical reserve framework can include
- Common mistakes that leave portfolios exposed
- How to apply these strategies to your portfolio now
- Final thoughts
Today, that discipline matters more. In Canada, CMHC reported that the purpose built rental vacancy rate increased from 2.2% in 2024 to 3.1% in 2025. Supply growth, slower population growth, and softer renter formation all played a role. At the same time, rental conditions diverged sharply by market, with Toronto at 3.0%, Vancouver at 3.7%, and Calgary and Edmonton around 5.0% in CMHC reporting. These numbers do not suggest investors should retreat from real estate. They show why portfolios need to be built to absorb change rather than depend on ideal conditions.
Real estate portfolio protection refers to the deliberate practice of managing risk so returns hold up when conditions change, not just when they cooperate. Protecting a real estate investment portfolio is fundamentally about three outcomes. First, it means reducing concentration risk, so one local shock, such as a single weak submarket or tenant segment, does not affect too much capital at once. Second, it means preserving cash flow when rent growth slows, vacancies rise, or operating expenses increase faster than income. Third, it means keeping optionality: the ability to hold through pressure, refinance on better terms later, or reposition an asset instead of becoming a forced seller. Together, these three outcomes are what separate portfolios that survive a downturn from those that get forced into distressed decisions during one, regardless of how strong the underlying property or market once looked.
This article focuses on practical, real world risk management techniques tailored for real estate investors. The goal is not to make a portfolio risk free, because that does not exist. The goal is to make your portfolio resilient enough to handle market fluctuations, property level surprises, financing stress, and weather related events without undermining long term returns.
Portfolio protection is not defensive thinking. In real estate, it is the operating system that allows investors to stay invested, protect cash flow, and create opportunities when weaker owners are forced to react.
Why portfolio protection matters more in the current market
After a long period when limited supply supported landlords in many cities, conditions are becoming more mixed. CMHC noted that Canada’s purpose built rental supply grew by 4.1% in 2024, the largest increase in more than 30 years, while average rent growth for a two bedroom unit slowed to 5.4% from 8% in 2023. More supply is healthy for the market over time, but it also means investors need to compete harder on leasing, tenant retention, and property positioning in the near term.
That shift changes the math of risk. A property purchased assuming continuous rent acceleration and near full occupancy may still work, but with less margin for error. Newer buildings can face lease up pressure. Assets near post secondary institutions can feel changes in student demand. Higher rent units may absorb more slowly than more affordable stock. Those are not abstract risks. They affect revenue, financing flexibility, and exit timing directly.
At the financing level, regulators and lenders are watching borrower stress more closely. OSFI’s 2025 to 2026 risk outlook highlighted mortgage delinquency trends and increased attention to lender risk management, including vulnerable areas such as condos and variable rate mortgage segments. For investors, the takeaway is simple. The capital environment is less forgiving than when rates were low and refinancing was easy. A solid property can become a problem if leverage, maturity timing, and reserves are not managed carefully.
There is also the growing importance of climate and catastrophe exposure. FEMA’s floodplain guidance is a reminder that hazard risk is not theoretical, and in higher risk areas lenders may require flood insurance. For investors, insurance should be viewed as part of portfolio infrastructure. The right coverage does not only help replace physical damage. It can also determine how quickly income recovers after a disruption and whether a setback becomes a temporary interruption or a prolonged capital event.
Strategy 1: Diversify beyond property count
The first and most effective way to protect a real estate portfolio is diversification, but many investors apply the idea too narrowly. Owning several properties does not automatically mean you are diversified. If those assets are all in one city, one asset class, one tenant profile, or one financing structure, you may still carry significant concentration risk. Diversification in real estate should be deliberate, not cosmetic.
A useful framework is to diversify across geography, property type, tenant profile, rent band, and lease structure. Geography matters because local employment trends, municipal policy, migration flows, and new construction pipelines can vary substantially. Property type matters because multifamily, student housing, industrial, office, and retail each respond differently to economic changes. Tenant profile matters because a portfolio that depends on one income segment or one demographic can be more exposed when affordability or employment conditions shift.
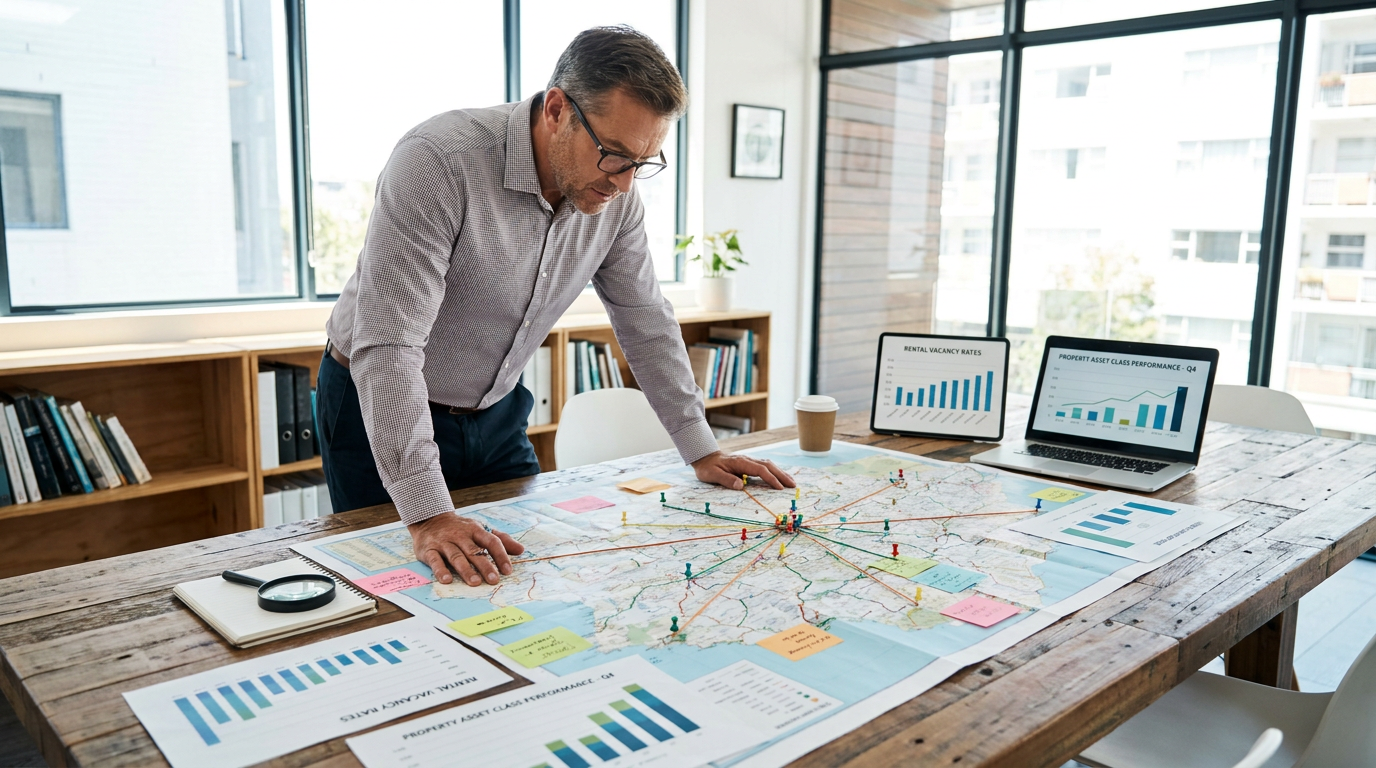
CMHC’s market reporting makes this point clearly. Vacancy pressures are not uniform. Some major centres have seen larger increases than others, and higher priced units have often faced weaker absorption than more affordable inventory. A landlord concentrated in one expensive submarket may feel pressure much sooner than one with mixed exposure across price points and cities. Diversification does not eliminate local downturns, but it can prevent one local downturn from defining total portfolio performance.
What diversification looks like in practice
For a smaller investor, diversification may begin with one simple decision. Instead of buying a second property in the same neighborhood because it feels familiar, consider a different submarket with a different demand driver. A downtown condo rental may perform very differently from a suburban multifamily asset serving long term family renters. Likewise, an area tied closely to university demand may not behave the same way as a neighborhood supported by healthcare, logistics, or government employment.
For larger investors, diversification should also include capital stack design. Having every property financed with the same lender, the same maturity window, or the same variable rate exposure can create hidden concentration. If market conditions tighten at the wrong time, refinancing several assets at once can turn an otherwise manageable cycle into a portfolio wide issue. Staggered maturities and mixed debt structures can be as important as geographic spread.
There is also a pricing segment dimension. In many markets, more affordable rentals remain structurally better supported than premium product because the demand pool is wider. That does not mean high end assets should be avoided. It means investors should understand how exposure is distributed. A portfolio tilted entirely toward one rent tier may be more sensitive to lease up pressure, household formation changes, or renter affordability constraints.
A practical diversification checklist
- Review what percentage of portfolio income comes from one city or region.
- Measure concentration by property type, not just by number of properties.
- Track exposure by tenant demographic and rent band.
- Review debt maturities to avoid clustering.
- Set maximum concentration limits before your next acquisition.
The important point is not to diversify for appearance. It is to diversify where cash flow risk actually lives. In real estate, that risk often sits in location, tenant demand, and financing structure more than in unit count alone.
Strategy 2: Treat insurance and hazard planning as core infrastructure
Many investors buy insurance because they need to. Sophisticated investors review insurance because they understand it protects continuity, lender relationships, and long term equity. In an era of rising catastrophe losses and climate related volatility, insurance is not an administrative task. It is a strategic component of portfolio defense.
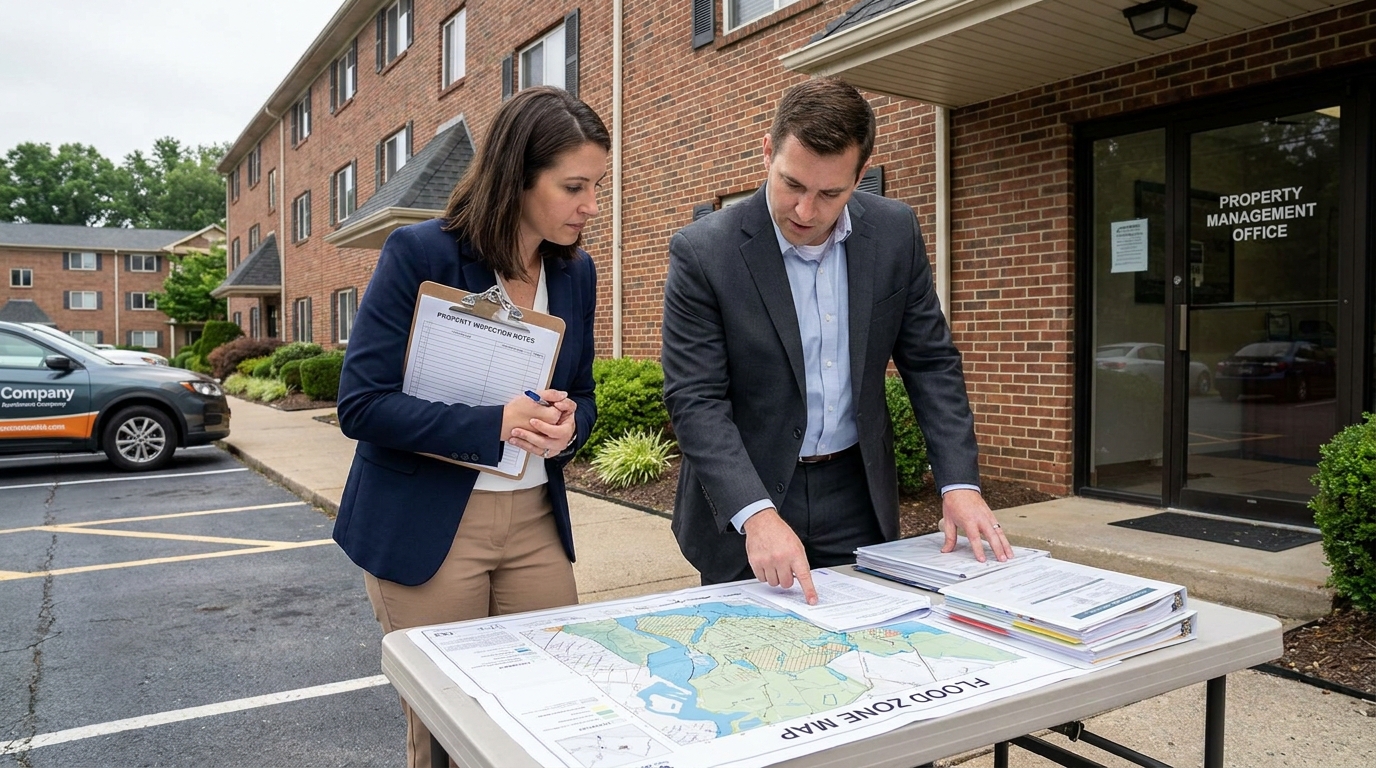
FEMA’s floodplain guidance is a useful benchmark for thinking about physical risk. Properties in Special Flood Hazard Areas may face lender driven flood insurance requirements, and the operational consequences of underestimating flood exposure can be severe. Yet flood risk is only one layer. Wind, wildfire, sewer backup, hail, water ingress, liability claims, equipment breakdown, and business interruption all deserve structured review based on each property’s profile.
One of the biggest misconceptions in real estate risk management is that having insurance means being protected. That is only true if the policy matches the actual risk. Underinsurance, outdated replacement cost assumptions, exclusions, sublimits, and large deductibles can all create major out of pocket losses. Business interruption coverage can be especially important for income producing assets because physical repairs are only part of the financial damage after a serious event.
What to review in your insurance program
Start with replacement cost adequacy. Construction costs, labor shortages, and building code changes can make older coverage assumptions obsolete. A policy that was reasonable two years ago may no longer reflect what it would actually cost to rebuild or restore income. Next, confirm whether flood coverage is included, excluded, or subject to separate terms. In weather exposed regions, this deserves direct attention rather than assumption.
Liability limits should be reviewed relative to portfolio scale and tenant traffic. Investors with mixed use properties, larger multifamily sites, or assets with common amenities may need stronger liability protection than they initially arranged. It is also wise to review ordinance and law coverage, equipment breakdown, and loss of rent or business interruption provisions. The difference between a minor operating event and a major capital setback often comes down to policy detail.
Hazard mapping should be part of due diligence and annual review. Flood zones, drainage conditions, wildfire interfaces, and local infrastructure weaknesses can all affect insurability and recovery timelines. If an asset sits in a higher risk area, mitigation steps such as drainage upgrades, backflow prevention, roof reinforcement, or emergency response planning may improve resilience and in some cases help manage premiums over time.
Insurance should support portfolio strategy
The deeper point is that insurance decisions should align with holding strategy. If you own older assets with strong cash flow but deferred capital needs, policy design and deductible tolerance should reflect that reality. If you own newer properties in lease up, business interruption protection may be especially important because lost occupancy momentum can be difficult to recover. If you are using leverage aggressively, lenders may impose requirements, but you should still evaluate whether those minimums are sufficient for your own risk tolerance.
Insurance is one of the few tools that can meaningfully reduce the financial impact of low probability, high severity events. Used well, it helps protect both the asset and the investor’s ability to remain strategic under stress.
Strategy 3: Use conservative leverage and stress test every asset
Leverage is one of the most powerful tools in real estate, and one of the most dangerous when used without margin. Debt magnifies returns when occupancy is strong, financing is stable, and values rise. It also magnifies pressure when interest rates increase, vacancies rise, or refinance proceeds shrink. That is why leverage discipline belongs at the center of portfolio protection.
OSFI’s recent attention to mortgage lender practices and delinquency trends reflects a broader truth. Financing risk does not only come from poor assets. It can come from good assets financed too tightly for changing conditions. Investors who rely on optimistic rent assumptions, short term refinancing windows, or thin reserves may discover that temporary operating softness becomes a balance sheet problem quickly.
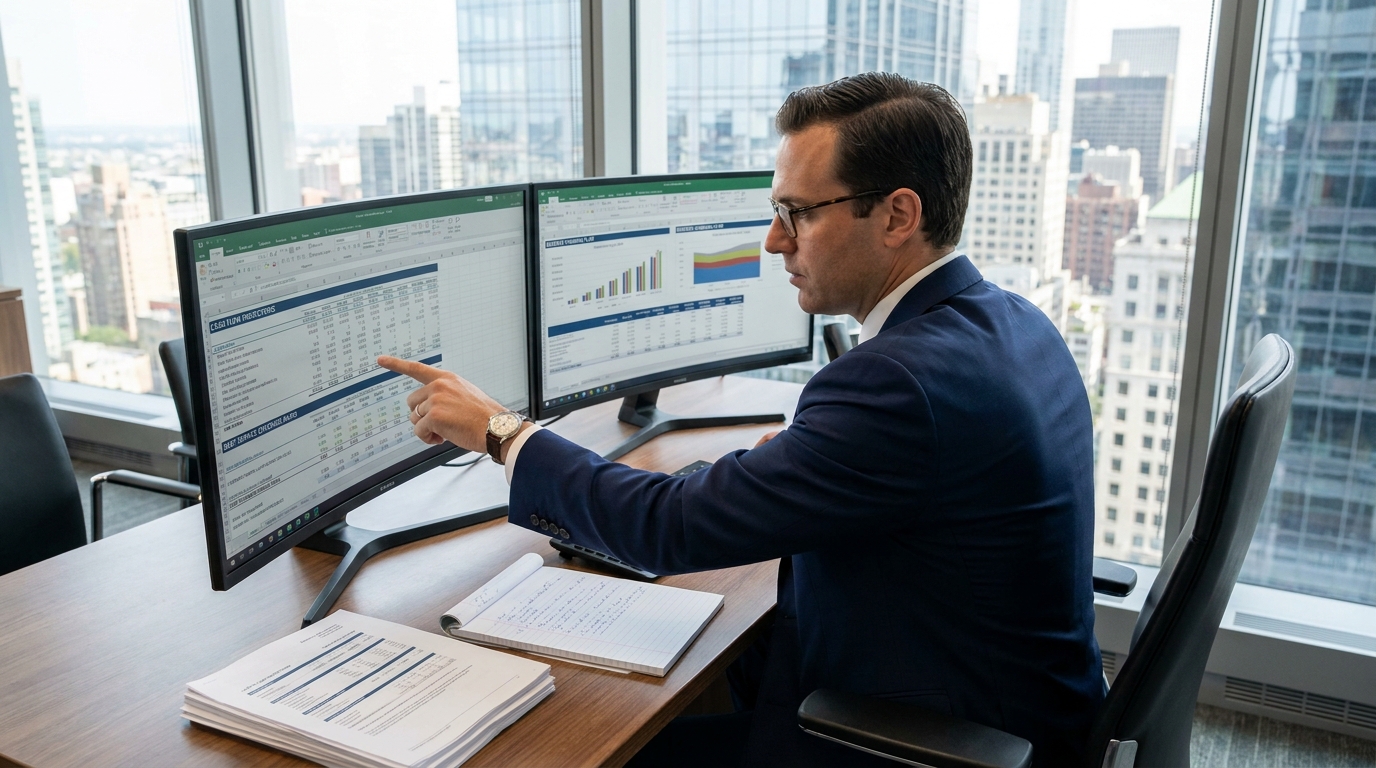
A robust approach starts with stress testing. Before acquisition, and then again before refinance or major capital decisions, investors should model debt service under less favorable conditions. That means testing for higher rates, lower renewal rents, slower lease up, higher concessions, increased operating costs, and elevated vacancy. The objective is not pessimism. It is knowing whether the property still works if the market gives you an average outcome instead of a perfect one.
Key leverage metrics that matter
Two of the most important metrics are loan to value ratio and debt service coverage ratio. A conservative loan to value ratio gives you more room if valuations soften. A stronger debt service coverage ratio gives you more breathing room if rents dip or expenses rise. These are not abstract underwriting terms. They are practical indicators of whether a property can carry stress without requiring emergency capital.
Reserve policy is equally important. A vacancy reserve covers periods when units sit empty longer than expected. A capital expenditure reserve supports roofs, mechanical systems, common area upgrades, and unforeseen repairs without forcing expensive short term borrowing. Investors often focus on purchase price and gross yield while underestimating how much protection simple liquidity can provide. In many cases, reserves are what allow an investor to act rationally while others are under pressure.
Maturity planning is another overlooked area. If too much debt comes due during a weak refinancing window, investors can be forced into poor choices. Staggering maturities and engaging lenders early can reduce that pressure. It is also wise to know what your refinance looks like under a more conservative valuation and debt service assumption before you need to negotiate from that position.
A simple stress testing approach
- Model occupancy with vacancy at least 2 to 5 percentage points above current levels, depending on market conditions.
- Reduce projected rent growth and include lease up delays for new or repositioned units.
- Increase interest rate assumptions above current quotes.
- Add higher insurance, utilities, and maintenance costs.
- Test whether reserves remain sufficient after these adjustments.
If a deal only works under ideal assumptions, it is not well protected. Conservative leverage does not eliminate upside. It preserves the right to keep the asset long enough for upside to materialize.
Strategy 4: Protect cash flow through disciplined asset management
Portfolio protection does not stop after closing. It is often won or lost in day to day operations. Investors who manage assets actively tend to protect income better because they see pressure earlier, respond faster, and keep tenant experience aligned with market competition. Investors who treat management as a back office function often discover problems after revenue has already slipped.
CMHC’s recent rental reporting highlights how quickly conditions can shift as new supply enters a market. New buildings can create competition not only on rent, but also on incentives, amenities, and expectations around service quality. In that environment, strong property level management is a direct form of risk management. It helps preserve occupancy, reduce turnover costs, and maintain the revenue line that supports valuation and financing.
Start with tenant retention. Turnover is expensive. It creates vacancy downtime, leasing costs, repairs, cleaning, and sometimes incentives to refill the unit. A modest investment in responsiveness, common area quality, preventative maintenance, and clear communication can often produce stronger net returns than chasing headline rent increases while tenant satisfaction weakens. Stability is valuable, especially when markets become more competitive.
Operational habits that reduce portfolio risk
Track rent performance by unit type, not only by building average. In softer conditions, one unit mix may underperform while another remains stable. Review leasing velocity against local competition each month. Monitor renewal rates, delinquency, concessions, maintenance requests, and days to turn a vacant unit. These are operating metrics, but they are also early warning indicators for portfolio risk.
Preventative maintenance deserves more respect than it often gets. Deferred maintenance does not save money in a meaningful sense. It usually shifts costs into the future while adding operational friction in the present. Roof leaks, aging boilers, drainage problems, exterior deterioration, and repeated in suite issues can all increase vacancy, accelerate capital costs, and reduce financing flexibility. Lenders and buyers notice property condition quickly, especially in a slower market.
Capital expenditure planning should be strategic rather than reactive. If newer stock is competing aggressively in your submarket, an older property may need targeted upgrades to protect occupancy and pricing. That does not mean over improving. It means understanding what matters to your tenant base and investing where retention and leasing performance improve. Security, lighting, common areas, in suite durability, and energy efficiency often have stronger return profiles than cosmetic spending alone.
Management should reflect tenant demand, not owner preference
One of the most common mistakes in real estate operations is assuming the owner’s view of value matches the tenant’s. In reality, tenant priorities are specific. Families may prioritize storage, parking, school access, and quiet. Young professionals may prioritize transit access, package handling, and digital convenience. Students may prioritize furnished options, internet reliability, and flexible timing. Understanding those differences improves leasing strategy and reduces vacancy risk.
Asset management also includes repositioning decisions. If a building is structurally sound but misaligned with current demand, a value add strategy can protect returns more effectively than passive holding. That might mean changing unit mix, improving amenity relevance, upgrading energy systems, or targeting a different renter segment. A portfolio stays resilient when owners are willing to adjust to what the market is telling them rather than defend yesterday’s assumptions.
Strategy 5: Keep liquidity and scenario plans for the unexpected
The final strategy is simple, but it is often the difference between control and distress. Keep liquidity. Real estate is attractive partly because it can produce durable cash flow, but the asset itself is illiquid and events rarely arrive on a convenient schedule. Repairs, legal issues, vacancies, insurance deductibles, tax changes, refinancing gaps, and market dislocations all require cash before they produce clarity.
Liquidity is a protection strategy because it buys time. Time to complete repairs properly. Time to lease units without panic pricing. Time to refinance from a position of preparation rather than desperation. Time to pursue a repositioning strategy instead of accepting a weak sale. In cyclical asset classes, survival is often less about being right than about staying funded long enough for conditions to normalize.
Scenario planning makes liquidity more effective. Investors should know in advance what actions they would take if vacancy rises above plan, if a major capital item fails, if rates remain higher for longer, or if a local submarket sees sudden competitive supply. A portfolio response plan does not need to be overly formal, but it should establish priorities. Which assets receive capital first. Which projects pause. Which loan discussions begin early. Which operating expenses are variable and which are not.
What a practical reserve framework can include
- An operating reserve sized to cover several months of property expenses and debt service.
- A separate capital reserve for planned and unplanned building work.
- A vacancy and leasing reserve for markets facing softer absorption.
- Access to contingent liquidity, such as an undrawn line, if appropriate.
- A documented playbook for adverse scenarios and decision triggers.
Liquidity also creates offensive flexibility. When markets soften, well capitalized investors can negotiate better acquisitions, refinance from strength, and fund upgrades that weaker owners delay. The same cash reserve that protects downside can improve future upside. That dual role is why sophisticated investors treat liquidity as a strategic asset rather than idle capital.
Common mistakes that leave portfolios exposed
Several recurring mistakes undermine otherwise solid real estate portfolios. The first is confusing a favorable recent market with a low risk strategy. Low vacancy in one year does not guarantee future safety, especially when new supply, migration changes, or affordability pressures begin to alter demand. Investors should avoid underwriting tomorrow using only yesterday’s strongest conditions.
The second mistake is believing diversification simply means owning more doors. A portfolio with ten units in one building is not necessarily safer than a portfolio with four units spread across different submarkets and tenant profiles. What matters is how many distinct risks affect the income stream, not just how many assets appear on a schedule.
The third mistake is overreliance on leverage. Higher debt can improve returns on paper, but it reduces the ability to absorb delays, disruptions, and refinancing pressure. In volatile conditions, the most valuable financial trait is not maximum leverage. It is the capacity to remain patient while others lose optionality.
The fourth is treating maintenance and insurance as cost centers to minimize rather than protective systems to optimize. Deferred maintenance raises both physical and financial risk. Underinsurance does the same. Neither issue is usually visible in a strong market, which is exactly why they become expensive later.
How to apply these strategies to your portfolio now
The best portfolio protection plans are actionable. Begin with a portfolio review rather than a market forecast. Identify where income concentration is highest. Review which assets are most exposed to softening vacancy, lease up risk, or local supply competition. Map debt maturities, rate exposure, and refinance sensitivity. Compare insurance coverage against current replacement cost, flood or hazard exposure, liability profile, and business interruption needs. Then assess reserves relative to realistic stress scenarios.
From there, prioritize the adjustments with the strongest protective value. For some investors, that will mean reducing concentration in a single city or tenant segment. For others, it may mean reworking debt structure before maturities become urgent. For owners of older buildings, the highest value action may be preventative capital work that reduces operating disruptions and preserves occupancy. For portfolios in weather exposed areas, it may be an insurance and mitigation review.
Protection does not require perfection. It requires honest underwriting, disciplined operations, and enough liquidity to avoid forced decisions. Investors who build those habits consistently tend to hold through volatility more effectively and capture better long term outcomes.
Final thoughts
Real estate wealth is built not only through acquisition, but through endurance. Markets change, tenant demand evolves, and financing conditions tighten and ease in cycles. Investors who rely on momentum alone often discover that returns are fragile. Investors who diversify thoughtfully, insure properly, manage leverage conservatively, operate assets actively, and maintain liquidity give themselves a much stronger platform for compounding.
The current environment reinforces that lesson. Rising vacancy in parts of the Canadian rental market, uneven absorption across segments, closer lender scrutiny, and growing climate related risk all point toward the same conclusion. Protection is not a secondary concern. It is a central investment function.
If you want your portfolio to perform over the long term, focus less on predicting the next headline and more on strengthening the structure that sits beneath returns. In real estate, resilience is often the most valuable edge an investor can build.
No Comment! Be the first one.