What the Bank of Canada’s Rate Hike Means for Property Investors
Every real estate strategy eventually runs into the cost of money, and this week that cost moved against investors. Bank of Canada governor Tiff Macklem told the House of Commons finance committee that the central bank can no longer look past an energy driven inflation shock, a signal that should reset expectations for anyone holding or planning to acquire property in this market.
Last week the Bank raised its policy rate by 25 basis points to 2.5 per cent, its first increase since 2023. For leveraged investors, that is not a rounding error. Borrowing costs on variable rate mortgages, lines of credit tied to investment properties, and construction financing all move in step with that policy rate. A quarter point hike arriving after years of relative stability tells us the easy assumptions about financing cost are no longer safe to make.
The reasoning behind the move matters as much as the move itself. Inflation has held near three per cent for three straight months, driven by higher oil prices after renewed conflict in the Middle East disrupted global refinery capacity. The Bank’s October outlook now projects inflation climbing toward 3.5 per cent by year end and staying elevated through much of 2027, well past the earlier call for a return to target by early 2027. That is a meaningfully worse inflation path than investors were pricing just a few months ago, and it raises the odds of further tightening ahead.
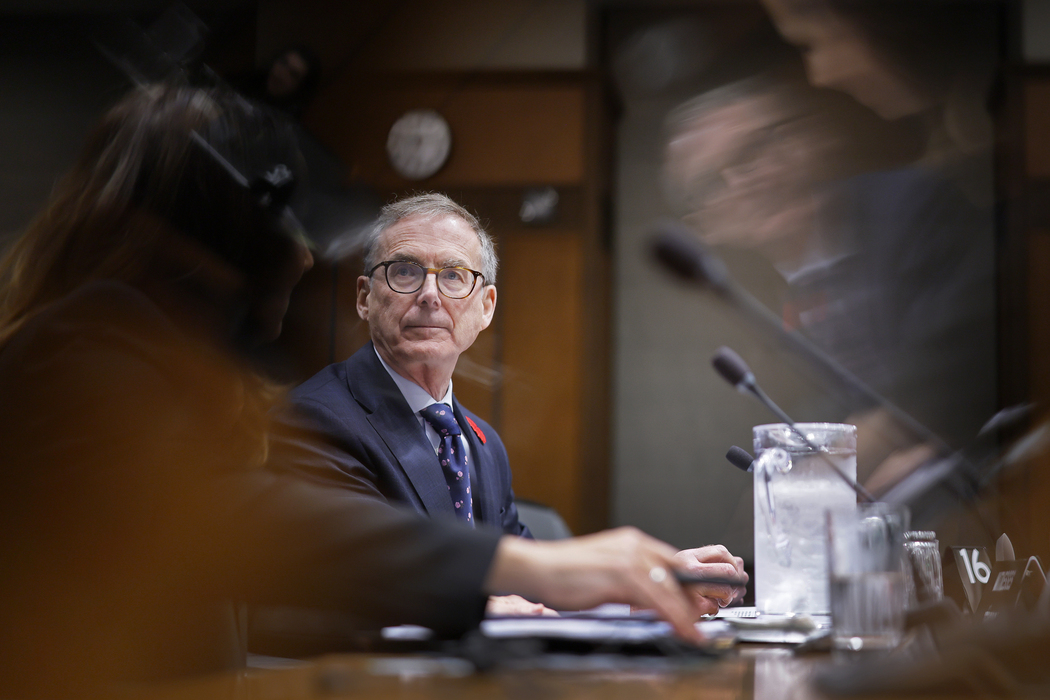
Senior deputy governor Carolyn Rogers framed this as a supply shock with real pass through risk, the concern that energy costs bleed into broader prices for goods and services. For investors, that distinction matters because it suggests the Bank is acting pre-emptively rather than reactively, which means policy could stay tighter for longer even if headline inflation stabilizes.
The most important thing we can do right now is make sure that we don’t have another period of persistent inflation that adds yet again to price levels.
What should disciplined investors take from this. First, revisit debt structure. Fixed rate financing locked in before this cycle looks increasingly valuable, and anyone renewing a mortgage or credit facility in the next year should stress test their numbers against a higher-for-longer rate environment rather than the gentler glide path previously forecast. Second, rental demand dynamics deserve a fresh look. Macklem noted consumer spending remains resilient and exports have strengthened, which supports household income even as affordability pressure mounts, a combination that historically sustains rental demand even when ownership affordability tightens further.
Third, factor in the trade overhang. Macklem was notably more guarded on the Canada-U.S. trade relationship, acknowledging that new tariffs will likely slow growth even as he expressed hope for resolution. Investors with exposure to markets tied to export-driven employment, particularly in Ontario and parts of the West, should weigh that softer growth backdrop against the higher financing costs now in play.
The opportunity in moments like this rarely comes from reacting to the headline. It comes from recalibrating assumptions early, before the rest of the market adjusts. A higher and more persistent inflation path means a higher and more persistent rate path, and investors who price that in now will be better positioned than those waiting for confirmation.
Source: Financial Post, “Bank of Canada can no longer look through energy price shock”