
Real estate investing is often presented as a straightforward path to wealth creation. Buy well, finance intelligently, manage efficiently, and let appreciation and cash flow do the rest. In reality, the legal side of property ownership is where many investors lose margin, time, and in serious cases, the asset itself. A strong purchase price cannot compensate for a title defect, a prohibited use, a tenancy law violation, or a tax position that does not withstand scrutiny. Legal risk is not a side issue in real estate. It is part of the investment itself.
Table Of Content
- Why legal risk deserves the same attention as market risk
- The first misconception: real estate is not governed by one rulebook
- Title and ownership risk: the foundation of every deal
- Practical protections for title risk
- Zoning, land use, and building code risk
- Landlord and tenant compliance: where cash flow meets regulation
- Lease drafting is a risk management tool
- Fraud, wire risk, and anti money laundering exposure
- Controls that reduce fraud exposure
- Tax compliance is a legal risk, not just an accounting issue
- Foreign ownership and cross border transaction risk
- Consumer protection, disclosure, and representations
- Environmental and building condition liability
- How to build a legal risk management framework across the investment cycle
- At acquisition
- At financing
- During operations
- At exit
- A practical checklist for investors who want to protect returns
- The strategic perspective: legal discipline protects ROI
- Final thoughts
Legal risk in real estate investment is the risk that title defects, zoning restrictions, tenancy violations, tax non-compliance, fraud, or unclear ownership will reduce returns, delay a closing, or threaten the asset itself. It spans every stage of a deal: title and ownership verification, zoning and land use compliance, landlord and tenant law, anti money laundering and fraud controls, tax reporting, foreign ownership rules, and consumer disclosure obligations. Because real estate law in Canada is set at the federal, provincial, and municipal level simultaneously, the same investment strategy can be compliant in one city and prohibited in another. Recent policy shifts show the stakes are rising: Canada has extended its ban on foreign ownership of certain residential property to January 1, 2027, and enhanced mandatory tax disclosure rules received royal assent in 2023. Investors who manage legal risk treat it as part of underwriting, not an afterthought handled once problems appear.
That matters even more in Canada and across North America, where real estate is shaped by overlapping layers of law and regulation. Federal rules can affect foreign ownership, anti money laundering compliance, and tax reporting. Provincial and territorial laws govern landlord and tenant relationships, registration systems, and many core property rights. Municipalities control zoning, permits, occupancy, and building standards. Investors who assume one legal checklist covers every market are often the ones exposed to the most expensive surprises after closing.
This article provides a comprehensive guide to the main legal risks in real estate investment and the strategies investors can use to manage them proactively. The goal is not to turn investors into lawyers. The goal is to help investors think like disciplined operators who understand that risk adjusted returns depend on more than location and leverage. They also depend on compliance, documentation, and process.
Key principle: In real estate, legal risk rarely arrives as a single dramatic event. More often, it appears as a chain of overlooked details that erode returns over time or create liability at the worst possible moment.
Why legal risk deserves the same attention as market risk
Most investors spend considerable time evaluating market trends, financing costs, rental demand, and projected appreciation. Those are essential variables, but they are only part of the return equation. Legal failures can block redevelopment, delay closings, invalidate assumptions behind income projections, trigger fines, or create litigation costs that materially reduce net yield. A property that looks attractive on paper can become a weak investment if the legal groundwork was not completed properly.
Legal risk is also uniquely difficult because it does not always show up during underwriting in an obvious way. Zoning restrictions may not prevent a sale, but they may prevent the exact rental strategy that justified the price. A tenancy issue may not matter at acquisition, but it may become central once renovations begin. A tax reporting gap may not affect the first year of ownership, yet it can surface during an audit when the investor is already committed to a refinancing or exit. Unlike a simple operating expense increase, many legal issues compound over time.
In the current environment, investors also face a policy landscape that is becoming more active rather than less. In Canada, the federal government has extended the ban on foreign ownership of certain residential property to January 1, 2027. Authorities have also increased focus on beneficial ownership transparency, anti money laundering enforcement, disclosure obligations, and housing related consumer protection. The message is clear. Real estate is no longer treated only as a private asset class. It is also viewed through the lens of affordability, transparency, and financial integrity.
The first misconception: real estate is not governed by one rulebook
One of the most common and costly mistakes in real estate investing is assuming that property law is relatively uniform. Investors often move from one city to another or from one province to another expecting that what worked in one jurisdiction will work in the next. In practice, the legal framework is highly localized. Even sophisticated investors can underestimate how much local law affects use, operations, tenancy, renovation timing, and enforcement risk.
In Canada, each province and territory has its own residential tenancy legislation. That means eviction processes, rent increase rules, notice periods, maintenance obligations, deposit rules, and tenant protections are not identical across the country. Municipalities add another layer by controlling land use, short term rental restrictions, occupancy standards, parking requirements, and permit approvals. For investors pursuing value add strategies, this is critical. The same business plan may be feasible in one city and problematic in another.
Because of that, legal due diligence should never be reduced to downloading a standard lease and relying on a generic closing checklist. Real estate is hyper local from a legal standpoint. Investors who build a repeatable process around local counsel, local permit review, and market specific compliance tend to protect capital far more effectively than those who rely on assumptions.
Title and ownership risk: the foundation of every deal
Title risk is one of the oldest legal concerns in real estate, yet investors still underestimate it. Buying property without a clear understanding of what exactly is being transferred can lead to serious financial consequences. Title issues can include undisclosed liens, easements, restrictive covenants, boundary disputes, registration defects, fraudulent transfers, and competing ownership claims. Even when these issues do not invalidate ownership outright, they can limit financing options, restrict development potential, or complicate resale.
Title insurance is useful, but it should not be mistaken for a complete substitute for due diligence. It can help protect against certain title related losses, but it does not eliminate every operational, zoning, or contractual risk attached to a property. Investors should treat title insurance as one layer of protection within a broader review process. That process should include a title search, review of registered interests, survey or real property report analysis where relevant, and confirmation that legal access and boundaries align with the intended use.
Title fraud has become a more visible concern as well. Canadian consumer protection guidance has warned that title fraud and mortgage application fraud can cause major financial losses. Fraudsters may attempt to impersonate owners, forge documents, or manipulate financing structures. For investors, especially absentee owners or those holding multiple properties, the risk is not theoretical. A disciplined file management process, prompt registration review, identity verification, and secure communication with lawyers and lenders can reduce exposure substantially.
Practical protections for title risk
The best approach begins before the offer becomes firm. Investors should ensure that the purchase agreement allows enough time for legal review and due diligence. During that period, counsel should confirm ownership history, registered charges, pending claims where discoverable, and any restrictions that may affect intended use or redevelopment. If the property is income producing, title review should be coordinated with lease review so that legal possession and practical occupancy line up.
Where a deal involves unusual circumstances such as power of attorney signatures, estate sales, rapid resales, assignment structures, or a seller requesting urgency around funds, the investor should slow the process down rather than speed it up. Urgency is often where fraud risk enters. Strong investors know that preserving the right to verify is not a sign of hesitation. It is a sign of control.
Zoning, land use, and building code risk
Many real estate investment strategies are really land use strategies in disguise. An investor may think they are buying a duplex, but what they are actually buying is the right to operate a duplex within a particular regulatory framework. If that framework changes or was misunderstood from the start, the economics of the investment can shift immediately. Zoning and building code issues are therefore central to legal risk management, especially in value add, conversion, infill, mixed use, and short term rental models.
Zoning governs what can be built and how property can be used. It can control density, setbacks, parking, permitted uses, lot coverage, signage, accessory units, and more. Building codes and occupancy rules determine what is safe and lawful from a construction and habitation standpoint. Investors sometimes assume that if a property has been used in a certain way for years, that use is automatically legal. That is a dangerous assumption. Prior use does not always mean compliant use, and non conforming uses can create serious issues during renovation, financing, insurance renewal, or sale.
This is particularly relevant when investors plan basement suites, garden suites, rooming houses, mixed use conversions, or short term rental operations. A standard acquisition model may show strong cash flow based on added units or flexible use, but if permits are unavailable or the zoning framework prohibits that use, projected returns collapse. In some cases, municipalities can require costly remediation or cessation of use. In others, insurers or lenders may react negatively once the true use is known.
For that reason, zoning review should not be treated as a formality. It should be tied directly to the business plan. The question is not simply whether the property complies today. The question is whether the property legally supports the intended strategy over the investor’s hold period.
Landlord and tenant compliance: where cash flow meets regulation
For income property investors, landlord and tenant law is one of the most operationally significant legal risk categories. Rent collection, notices, deposits, maintenance, privacy, access, eviction procedures, and rent increase limits are all governed by statute and tribunal processes that vary by jurisdiction. Investors who treat tenancy compliance casually often discover that legal mistakes can delay enforcement, reduce recoveries, and intensify disputes with tenants.
In Canada, landlord and tenant obligations are defined largely by provincial and territorial legislation. That means there is no universal Canadian lease or one set of standard rules. On top of that, housing policy has increasingly moved toward stronger tenant protections and more formal oversight. The federal government has also backed tenant support initiatives, including a Tenant Protection Fund announced in Budget 2024. While that fund does not rewrite local tenancy law, it reflects a broader policy climate in which tenant rights, legal services, and housing transparency are receiving more attention.
Investors should understand that tenancy risk goes beyond eviction mechanics. Renovations, unit entries, maintenance standards, rent discount structures, utility allocation, and amenity changes can all have legal implications. The same applies to newer operating models such as furnished rentals, rent by room structures, and short term stays that blur the line between residential tenancy and hospitality use. A standard lease may not be enough if the investment strategy introduces a different category of legal obligation.
Lease drafting is a risk management tool
Leases are often treated as administrative paperwork, but they are one of the investor’s first lines of legal defense. A well drafted lease does more than record rent and term. It clarifies maintenance responsibilities, insurance obligations, default remedies, access rights, permitted use, assignment rules, notice procedures, and dispute frameworks. In commercial real estate, these details can materially affect NOI stability. In residential investing, they help align operations with statutory requirements and reduce ambiguity.
That said, no lease can override mandatory statutory protections where those protections apply. This is why local legal review matters. Investors should avoid copying documents from other deals or jurisdictions without confirming enforceability. Precision on the front end is far cheaper than dispute resolution later.
Fraud, wire risk, and anti money laundering exposure
Fraud is one of the most underappreciated legal and financial risks in modern real estate. Large transaction values, multiple intermediaries, time sensitive closings, and digital communications create a setting where a single lapse can lead to a major loss. Real estate fraud can involve forged ownership documents, identity theft, misrepresented mortgages, fake listings, altered payment instructions, or false income and asset information used to secure financing. The Financial Consumer Agency of Canada has specifically warned about title fraud and mortgage application fraud as sources of significant loss.
Investors should also pay attention to anti money laundering obligations and the broader regulatory scrutiny surrounding source of funds and beneficial ownership. Canada’s 2025 assessment of money laundering and terrorist financing risks identified real estate and mortgage channels as continuing risk areas. Official concern remains elevated around shell companies, beneficial ownership opacity, complex mortgage fraud, and laundering tied to tax evasion. In practice, that means investors, lenders, brokers, lawyers, and other professionals are operating in an environment where transactions may face greater verification requirements and more questions about who ultimately controls capital.
For legitimate investors, this should not be viewed as a nuisance. It should be seen as part of institutional grade transaction discipline. Clean money, clear structure, and complete documentation are not only about regulatory comfort. They also strengthen credibility with lenders, partners, and counterparties.
Controls that reduce fraud exposure
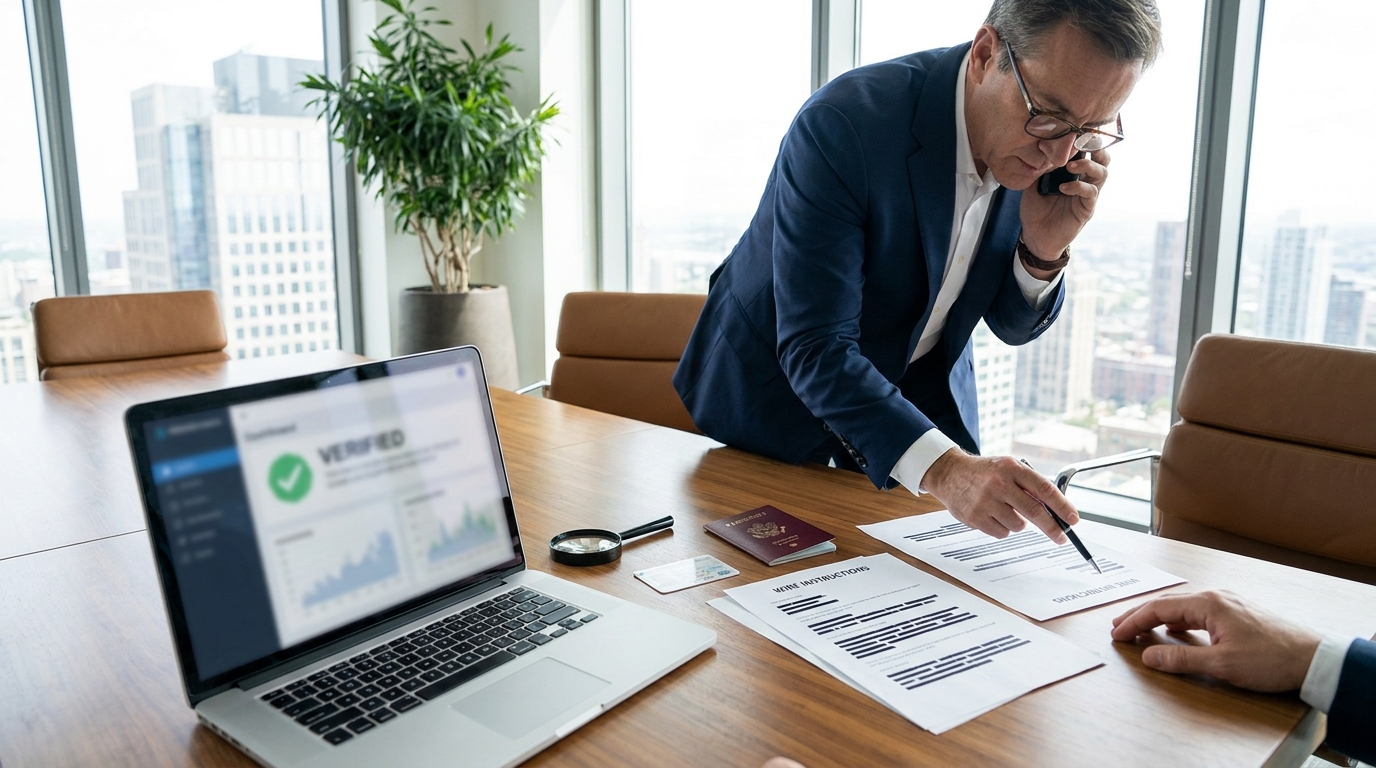
Fraud prevention starts with process. Investors should independently verify wire instructions through known phone numbers, not by replying to email chains. Sensitive payment changes should trigger mandatory callback procedures. Identity documents and entity records should be reviewed carefully, especially where counterparties are recently formed companies, nominees, or intermediaries not clearly tied to the property. Investors using corporations, trusts, or joint ventures should keep beneficial ownership records current and accessible.
It is also prudent to align legal, lending, and accounting teams so that unusual facts are flagged early. If income documents appear inconsistent, if the seller’s urgency seems excessive, or if ownership structure changes shortly before closing, those signals deserve more scrutiny, not less. Strong risk management in real estate often comes down to the willingness to pause when something does not fit the normal pattern.
Tax compliance is a legal risk, not just an accounting issue
Investors frequently treat tax as a year end function. In reality, tax compliance should shape the transaction from acquisition to exit. Structure, financing, assignment rights, renovation plans, holding period, intended use, residency status, and partnership arrangements can all affect reporting obligations and after tax outcomes. More importantly, mistakes in these areas are legal and compliance problems before they become accounting problems.
In Canada, enhanced mandatory disclosure rules that received royal assent on June 22, 2023 increased reporting obligations for certain transactions and uncertain tax treatments. At the same time, authorities have shown greater attention to property flipping, assignment income, and other speculative profits. The practical implication is straightforward. Investors should not assume that a profitable strategy is automatically a compliant strategy. If a deal involves rapid resale, pre construction assignments, complex entity layering, or aggressive expense treatment, tax advice should be integrated early.
This is especially important for investors moving between personal ownership, corporate ownership, partnerships, and trusts. Each can have different implications for income characterization, financing, land transfer taxes in some jurisdictions, GST or HST questions where applicable, and reporting obligations. Tax planning should be documented, not improvised. That does not mean every investor needs an overly complex structure. It means every structure should have a clear business rationale and a defensible compliance framework.
Foreign ownership and cross border transaction risk
Cross border investing introduces another layer of legal complexity. Canada has tightened housing related rules in recent years, including extending the ban on foreign ownership of certain Canadian residential property to January 1, 2027. Investors sometimes misunderstand this area by assuming either that all foreign buyers are banned or that restrictions are easily bypassed through alternative structures. Neither view is reliable. The actual legal position depends on the property type, buyer status, exemptions, transaction details, and related rules that may apply in the jurisdiction.
Separate from housing purchase restrictions, foreign investors in larger or strategically sensitive transactions may also need to consider federal review under the Investment Canada Act. While that regime is not aimed at every ordinary property purchase, it can matter for larger commercial deals, joint ventures, development platforms, or transactions involving assets with national security sensitivity, data implications, or broader economic relevance. The lesson for investors is that cross border capital requires a more structured legal approach from the start.
Domestic investors partnering with foreign capital should also be careful. Even if the local operating partner is compliant, the overall transaction may still trigger restrictions, disclosure obligations, or enhanced scrutiny depending on ownership and control. That makes beneficial ownership documentation and legal review essential components of pre acquisition planning.
Consumer protection, disclosure, and representations
Another area where investors can face liability is in the representations they make and the disclosures they receive or fail to verify. Consumer protection laws, disclosure regimes, and contractual misrepresentation claims can all affect a transaction. This is especially important in pre construction purchases, assignment deals, condo investments, mixed use projects, and any transaction marketed with strong income or appreciation claims.
Investors should read disclosure documents carefully and verify key assumptions independently. Rent guarantees, projected occupancy, development timelines, amenity promises, and assignment rights all need to be reviewed against the actual legal documentation. If a business case depends on verbal assurances from brokers, developers, or sellers that are not reflected in the contract, the investor is relying on weak protection. Sophisticated investing requires that important assumptions migrate from conversation into enforceable written terms.
The same principle applies when the investor becomes the seller or landlord. Marketing materials, listings, lease negotiations, and disclosure responses should be accurate and supportable. Overstating legality of use, downplaying known defects, or making casual promises about permits or redevelopment potential can create liability that survives the transaction itself.
Environmental and building condition liability
Not every legal risk begins with a contract. Some arise from the physical condition of the asset. Environmental contamination, unsafe systems, unpermitted work, fire code deficiencies, mould issues, asbestos, and structural failures can all create legal and financial exposure. In commercial real estate, environmental liability can be especially serious because cleanup obligations may attach to owners and sometimes occupiers regardless of whether they caused the original problem.
Residential investors are not immune. A basement conversion completed without permits can trigger compliance action. Inadequate life safety systems can affect insurance and occupancy. Building condition issues can also lead to disputes with tenants, contractors, municipalities, insurers, and lenders. What begins as a maintenance problem can quickly become a legal one if habitability, disclosure, or negligence concerns emerge.
The right response is disciplined technical due diligence. Property condition assessments, environmental reviews where appropriate, permit history checks, and contractor oversight should be standard in deals where risk justifies the cost. This is particularly true when buying older assets, repositioning underperforming buildings, or inheriting uses that may not have been fully documented by prior owners.
How to build a legal risk management framework across the investment cycle
The most effective investors do not address legal issues only when a problem appears. They build legal risk management into each stage of the investment cycle. That means acquisition, financing, operations, and exit all have their own control points. A structured framework does not eliminate uncertainty, but it reduces the chance that preventable issues damage returns.
At acquisition
Before closing, investors should confirm ownership, title status, zoning compatibility, existing leases, permit history, tax position, and financing conditions. This is the time to identify whether the intended business plan is legally viable. If the numbers only work under assumptions that have not been verified, the underwriting is incomplete. Counsel, accountants, and property specific consultants should work from the same facts so that legal, tax, and operational advice align.
At financing
During financing, investors should expect greater scrutiny around income documentation, source of funds, beneficial ownership, and use of proceeds. This is not only about satisfying lenders. It is also about creating a clean record that can withstand future questions from auditors, regulators, insurers, or partners. Any mismatch between the disclosed use of property and the actual business model should be resolved before funds are advanced.
During operations
Operationally, risk management depends on consistency. Leases should be current and jurisdiction appropriate. Notice procedures should be documented. Maintenance logs, inspections, contractor agreements, and insurance reviews should be organized and retained. If a dispute arises, the investor who can produce a clear record is usually in a much stronger position than the investor who relies on memory and informal communication.
At exit
At disposition, legal planning matters again. Investors should review assignment clauses, tax consequences, disclosure obligations, tenancy status, and any unresolved compliance items before listing or closing. A preventable issue discovered during a buyer’s due diligence can weaken price, delay closing, or force concessions. Clean exits usually begin months before the property actually goes to market.
A practical checklist for investors who want to protect returns
While every asset and market is different, a practical legal risk framework usually includes several recurring disciplines. These are not theoretical best practices. They are the habits that separate resilient investors from reactive ones.
-
Use local legal counsel who understands the province, state, and municipality where the property is located. Real estate law is too local for generic advice to carry the full load.
-
Match due diligence to the strategy. If the value depends on rezoning, adding units, repositioning tenants, or executing assignments, review those issues before the deal becomes unconditional.
-
Treat leases and contracts as operating tools, not boilerplate. Documentation should reflect the real business model and current legal rules.
-
Verify identities and funds independently. Fraud controls should be built into communication, payments, and closing procedures.
-
Document beneficial ownership and source of funds clearly, especially in partnerships, trusts, corporate structures, and cross border transactions.
-
Integrate tax advice early when deals involve flipping, assignments, uncertain classifications, or non standard structures.
-
Review insurance alongside legal risk. Coverage should align with actual use, occupancy, renovation plans, and liability exposure.
-
Maintain records rigorously. Strong files reduce friction with tenants, lenders, buyers, and regulators.
The strategic perspective: legal discipline protects ROI
From an investment standpoint, legal risk management is not a defensive afterthought. It is a return protection strategy. When investors underwrite deals based only on price, rent, and appreciation, they tend to overestimate upside and underestimate friction. Legal complexity is one of the main reasons projected returns fail to become realized returns. Closing delays, compliance costs, tribunal disputes, tax reassessments, and fraud losses do not just reduce profit. They consume management attention and restrict future optionality.
By contrast, investors who embed legal discipline into their process usually gain a strategic edge. They are better positioned to negotiate because they know where risk sits. They can move faster on good deals because their due diligence framework is already in place. They also tend to build stronger lender and partner relationships because their files are cleaner and their assumptions are more credible. In a competitive market, that level of preparedness can be as valuable as access to capital.
The broader trend across Canada and North America supports this approach. Regulation around housing, transparency, anti speculation, tenant protection, and financial integrity is not standing still. Investors should expect more scrutiny around ownership, use, funds, and reporting, not less. That does not make real estate less attractive. It simply means the premium now belongs to investors who operate with greater precision.
Final thoughts
Real estate remains one of the most compelling ways to build and preserve wealth, but it rewards discipline as much as optimism. The legal side of investing is where strategy meets reality. A property can be attractive, well located, and well financed, yet still produce disappointing results if title, zoning, tenancy, fraud, tax, or disclosure issues were not managed properly. Legal risk does not eliminate opportunity, but unmanaged legal risk can erase it.
The essential strategy is simple in principle, even if detailed in practice. Slow down enough to verify. Use local expertise. Align legal review with the actual business plan. Keep documentation strong. Treat compliance as part of underwriting, not as paperwork to handle later. Investors who do this consistently are not just reducing downside. They are building a more durable investment platform capable of protecting capital across market cycles.
In a market where policy, enforcement, and operating standards continue to evolve, that kind of legal discipline is not optional for serious investors. It is part of the edge.

No Comment! Be the first one.