Why Infrastructure Ontario’s $81.5M Office Buy Signals a Flight to Stability in Toronto’s Commercial Market
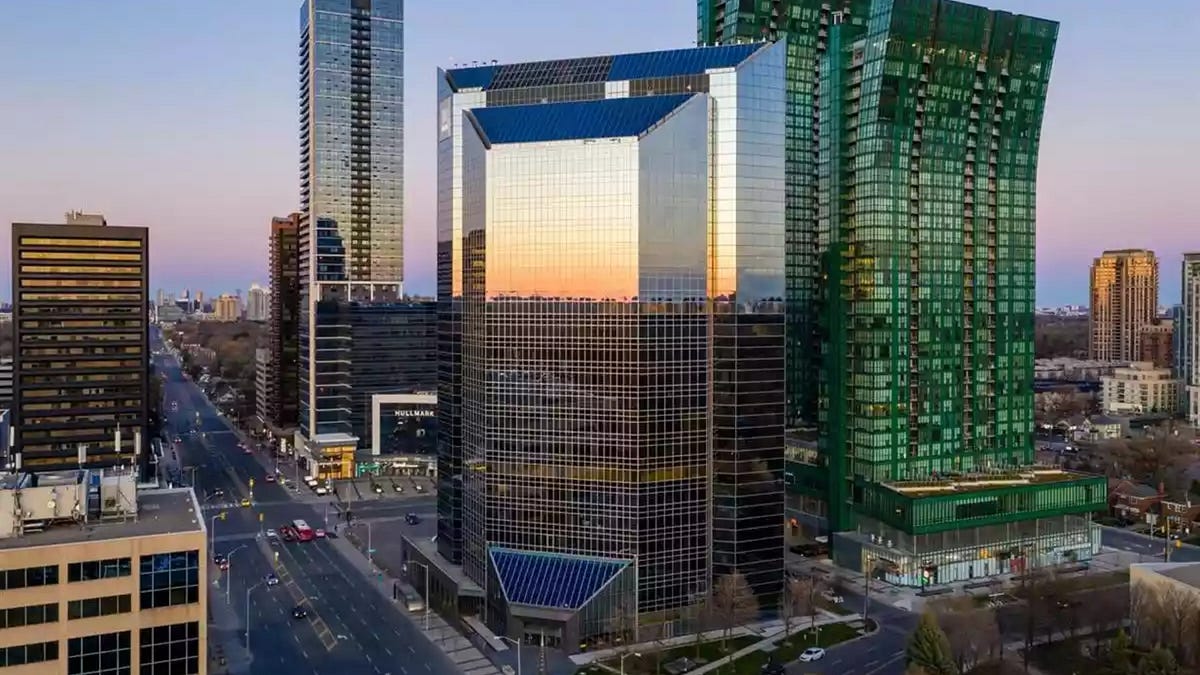
When a Crown corporation starts shopping for office towers, smart investors pay attention. Infrastructure Ontario has just closed on 25 Sheppard Avenue West, the 21 storey North York tower known as the Nestle Building, paying H&R REIT $81.5 million for an asset that tells us a great deal about where institutional confidence is landing in a still uneven office market.
The numbers are worth sitting with. At roughly $209 to $227 per square foot depending on whose leasable area figure you use, this is not a bargain bin distressed sale. It is a considered price for a Class A building anchored by Nestle’s Canadian headquarters and the Financial Services Regulatory Authority of Ontario, two tenants that bring the kind of covenant strength institutional buyers prize. Occupancy sits at 78.4 percent, respectable in a Toronto office market that has spent years working through post pandemic recalibration.
What makes this transaction more interesting than a single sale is the pattern around it. This is the second largest office trade in the GTA in the third quarter of 2026, trailing only GWL Realty Advisors’ $243.6 million purchase of 123 Front Street West and edging out BGO’s $75.5 million acquisition of 26 Wellington Street East, which was also offloaded by H&R REIT. Three sizeable office trades in one quarter, two of them from the same seller, is a signal that capital is still moving through this asset class even as headlines focus on vacancy.
For investors, the identity of the buyer matters as much as the price. Infrastructure Ontario has now acquired this building alongside 1 Queen Street East and 20 Richmond Street East, purchased earlier this year from CPP Investments for $145.5 million. A Crown corporation accumulating downtown and midtown office assets is a different kind of signal than a private fund doing the same. It suggests government is positioning for long term occupancy needs rather than chasing a cyclical discount, which tends to put a floor under values in the submarkets where it is active.
A seller moving two assets in one quarter while in the middle of its own takeover is not a sign of distress. It is a sign of discipline.
H&R REIT’s side of the story adds another layer worth watching. The trust is mid process on a $6.7 billion acquisition by GO Residential REIT and a consortium that includes Blackstone, Crestpoint, and PSP Investments, with a shareholder vote due next month and RBC Global Asset Management reportedly planning to vote against it. Shedding office assets like 25 Sheppard and 26 Wellington ahead of that vote reads as portfolio tidying, converting non core office exposure into balance sheet strength while the larger deal plays out.
For readers tracking where to deploy capital, the lesson is not that Toronto office is booming. It is that well tenanted, well located Class A buildings with government grade anchors can still command serious institutional interest, even in a market that remains selective. Price per square foot discipline, tenant quality, and buyer intent are doing more to explain this deal than any broad narrative about the sector’s recovery.