Institutional Landlords Face a Reckoning: What the Housing Backlash Means for Real Estate Capital
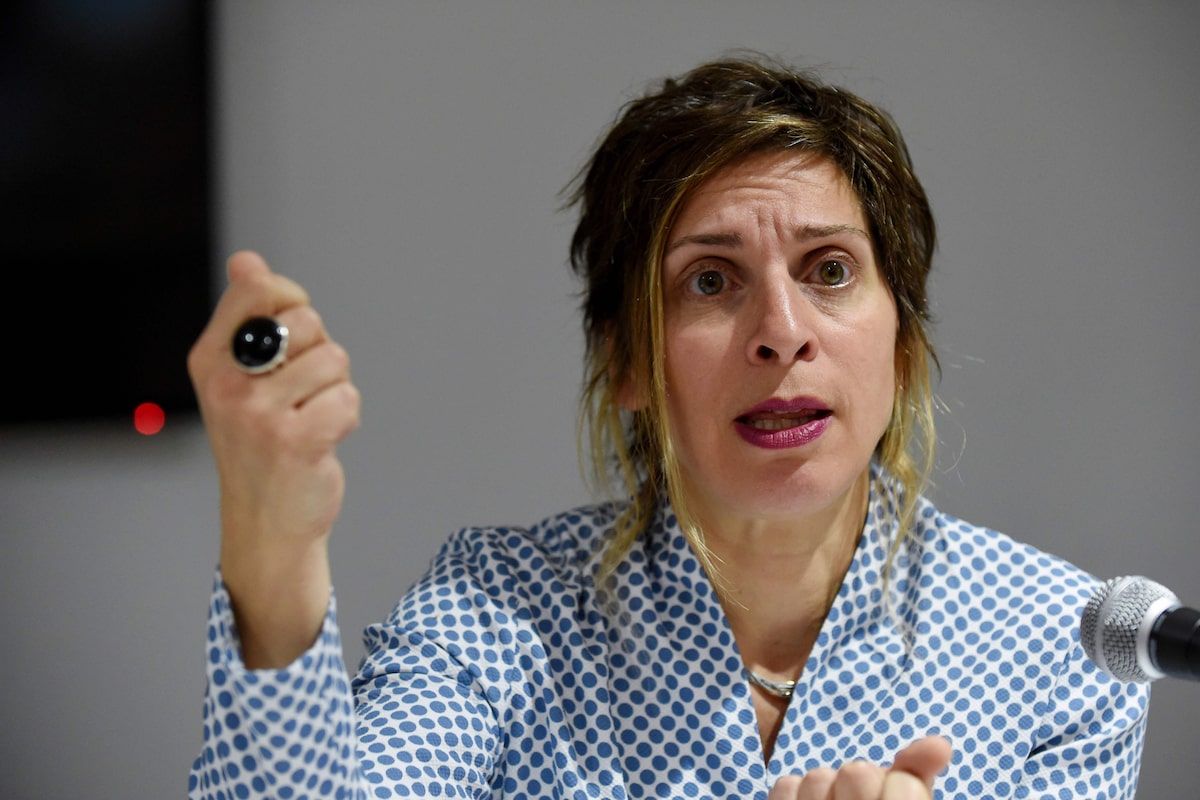
Every investment thesis eventually meets its political moment. For institutional rental housing in Canada, that moment has arrived. A growing chorus, most recently amplified by former UN housing rapporteur Leilani Farha, is making the case that the financialization of rental stock has gone too far. Investors who have built portfolios on this model should be paying close attention, not because the critique is wrong or right, but because public sentiment and regulatory risk are now material inputs to underwriting.
The numbers explain why this sector attracted capital in the first place. Residential real estate is the largest store of wealth on the planet, estimated at roughly US$287 trillion, more than twice global GDP. In Canada specifically, the shift has been dramatic. Financial firms owned virtually none of the country’s purpose-built rental stock in 1993. Today that figure sits near 20 per cent, concentrated enough that in some submarkets, such as Yellowknife, two firms control roughly 80 per cent of private rental supply. Concentration like that once looked like a moat. Increasingly, it looks like a target.
The mechanics behind this growth are worth understanding for anyone allocating capital to the space. Post-2008 near-zero rates pushed yield-seeking investors toward older apartment buildings with below-market rents and room to raise them. Lenders, in turn, reward rising rents with cheaper financing, since higher rents increase a building’s appraised value. That cycle, sometimes called displacement financing, has been efficient at generating returns. It has also been efficient at generating headlines. Research cited in the housing debate suggests eviction-filing rates roughly triple after a financial firm acquires a building, a statistic that regulators and tenant advocates are now citing in policy discussions about REIT taxation and rent governance.
There is a macro angle too. Residential investment now accounts for nearly 8 per cent of Canada’s economy, a larger share than the U.S. carried at the peak of its mid-2000s housing bubble, while Canadian households carry the highest debt load in the G7. That combination, high exposure plus high leverage, is precisely the sort of concentration risk that sophisticated allocators flag in any other asset class. Add to that a supply side that has not behaved as advertised, with unsold condo units in finished Toronto buildings hitting a record last year, and the simple “build more” thesis looks less like a safe harbor and more like its own risk.
Concentration that once looked like a moat increasingly looks like a target for regulators and tenant advocates alike.
None of this means the institutional rental model is finished. It means the risk premium attached to it is shifting, and the investors who price that shift early, through more conservative underwriting on tenant-turnover assumptions, closer attention to municipal and federal policy signals, and more diversified exposure across asset classes, will be better positioned than those who assume the last thirty years of cheap, concentrated growth simply continue. In real estate, as in any market, the moment a model draws this much political attention is usually the moment it stops being free money.
Source: The Globe and Mail, “Let’s call Canada’s housing crisis what it is”