Rate Hike Reality Check: What the BoC’s Move Means for Canadian Property Investors
The Bank of Canada’s quarter point increase to 2.5 per cent is a small number with outsized implications. For investors who track the full cycle of housing, from financing cost to resale velocity to luxury segment resilience, this week’s rate move is a signal worth reading carefully rather than reacting to emotionally.
The immediate effect is straightforward. Variable rate mortgages, which track the benchmark closely, are already moving upward, and fixed term products tied to bond yields have been climbing for months. For an investor underwriting a deal today, that means recalculating debt service coverage before assuming last quarter’s financing assumptions still hold. The spread between what a property could carry six months ago and what it can carry now is exactly the kind of gap that separates disciplined buyers from overextended ones.
What is more interesting to me is how unevenly this slowdown is landing. A Toronto family home recently sold $101,000 over its asking price in two days, proof that well positioned, well built inventory in strong school zones still commands competition regardless of rate direction. Meanwhile, in Ontario’s cottage country, real estate professionals are describing softer conditions as the season winds down, with some sellers now willing to negotiate rather than hold firm on price. Yet even there, the upper tier tells a different story. An 11.3 acre parcel on Lake Rosseau sold for 8.699 million dollars in late September, and brokers report first time cottage buyers paying above the 10 million dollar mark for trophy properties.
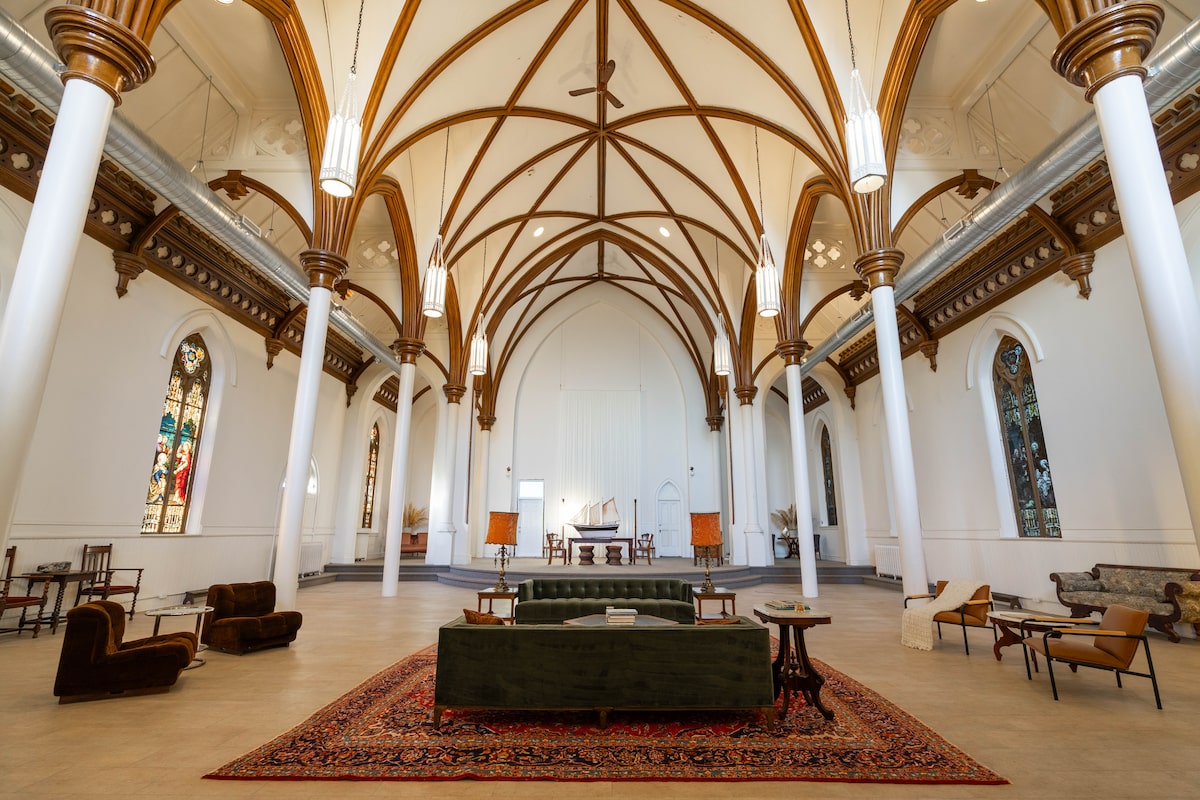
That divergence is the real lesson for anyone allocating capital into residential real estate right now. Rate sensitivity is not distributed evenly across price points or geographies. Buyers with substantial equity and less dependence on leverage are largely insulated from a 25 basis point move, which is why demand at the very top of the market, whether in recreational properties or well located urban homes, continues to hold firmer than the headline “slumping” narrative suggests.
At that level, the buyers are usually extra sharp and looking for fair value.
That broker’s observation about cottage country’s largest lakes applies more broadly than just recreational property. It describes exactly the kind of buyer behaviour investors should be watching for across every segment right now, discipline from those with the means to be patient, and softness opening up where leverage is doing more of the work. For investors, the strategy in a rising rate environment is not to retreat from the market but to reprice risk, lean toward assets with genuine scarcity value, and treat negotiating room from softer sellers as opportunity rather than a warning sign.
Source: The Globe and Mail.