Canada’s Price Correction Is Widening: What It Means for Investors Chasing the Next Entry Point
For a long stretch of this cycle, Canada’s housing correction has read like a two-province story: Ontario doing the heavy lifting, British Columbia drifting lower behind it, and everywhere else holding relatively firm. New data from the Canadian Real Estate Association suggests that narrative is starting to shift, and investors who are still pricing risk based on the old map need to update their assumptions.
Nationally, the benchmark price fell 0.9 percent in September to $651,400, putting the average home 22.5 percent, or roughly $189,000, below its peak. That headline number has been dominated by Ontario, which is now down 26.7 percent from its March 2022 high, a decline so severe it skews the national picture. BC remains a distant second at 16.7 percent off peak. The gap between those two markets and the rest of the country has been the defining feature of this correction, until now.
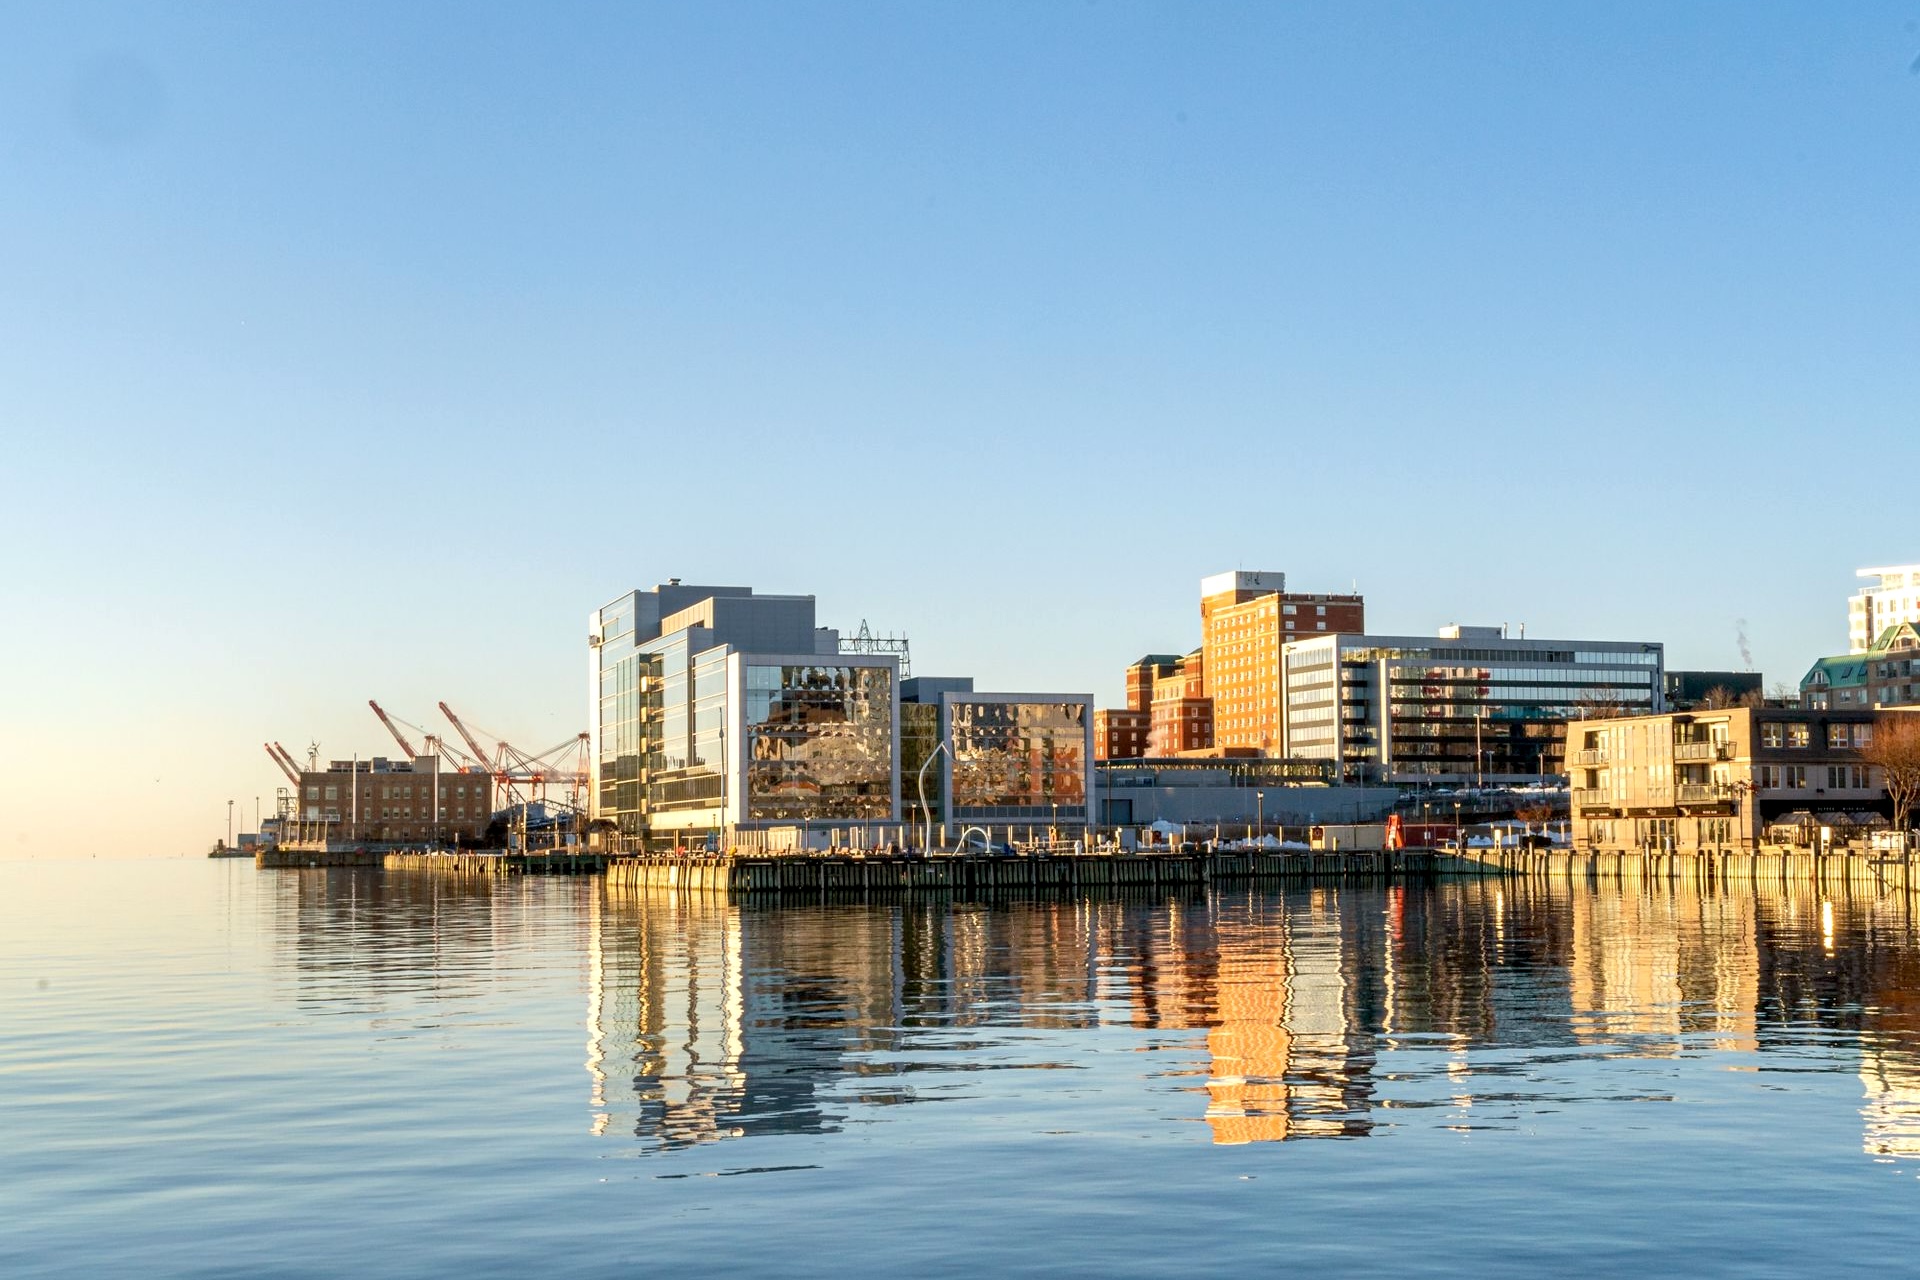
What caught my attention is Nova Scotia. Halifax posted the second-biggest monthly drop on record, pulling the provincial benchmark down 2.7 percent in a single month, the sharpest decline of any province in September. That is not noise. A market moving from single-digit resilience to a near 3 percent monthly drop, landing it 4.1 percent below its own peak, is the kind of inflection point that deserves attention before it shows up in everyone else’s models.
Eight of the nine CREA provincial indexes declined in September, with only Prince Edward Island posting a gain, and a modest one at that, following its own record monthly drop the month before. Saskatchewan and Ontario rounded out the three largest monthly declines. Yet annual figures tell a more complicated story: Newfoundland, Saskatchewan, and New Brunswick are still up year over year, proof that this is not yet a synchronized national downturn so much as a correction looking for its next region.
Corrections exist to resolve inefficiencies for buyers, not to satisfy a national average. Until a regional market repriced to where local incomes actually support it, treat any single month of calm as temporary.
For investors, the takeaway is about timing and dispersion, not panic. Ontario has already absorbed the bulk of the repricing, which means the risk-reward calculus there looks different than it did two years ago. The more interesting question is whether Atlantic Canada, flush with recent gains and now showing its first real cracks in Halifax, is entering the early stage of its own adjustment. Markets that climbed fastest on thin liquidity tend to be the ones that correct hardest once sentiment turns. Watching rental demand, local employment, and listing volume in Nova Scotia and Saskatchewan over the next few months will tell you more than the national average ever will. Capital tends to find its best entry points right around the moment everyone else stops watching.
Source: Better Dwelling, CREA data.