
Real estate investors often focus on location, financing terms, rental demand, and resale potential. Those variables matter, but taxation is what determines how much of the return you actually keep. A property that looks attractive on a gross yield basis can become mediocre once property taxes, income tax, capital gains exposure, transaction costs, and reporting obligations are properly modeled. Real estate taxation refers to the combined set of taxes and rules, including property tax, rental income tax, capital gains tax, and transaction taxes, that apply across a property’s acquisition, holding period, and sale. It shapes how an asset is acquired, whether it is held personally or through an entity, how renovation costs are treated, which expenses are deductible, whether depreciation should be claimed, and when the property should be sold. For serious investors, tax is not an administrative afterthought. It is part of underwriting, shaping the after-tax cash flow and return an investor actually keeps.
Table Of Content
- Why Real Estate Taxation Matters More Than Most Investors Realize
- The Core Taxes Real Estate Investors Need to Understand
- Property Taxes and Carrying Costs
- Rental Income Taxation
- Capital Gains on Sale
- Current Expenses Versus Capital Expenses: A Small Distinction With Big Consequences
- Depreciation and Capital Cost Allowance: Useful Today, Important Tomorrow
- The Principal Residence Exemption and Why Investors Must Treat It Carefully
- Capital Gain or Business Income: The Classification That Can Redefine Profit
- Common Myths That Lead to Costly Mistakes
- Mixed-Use Property: Where Many Investors Lose Clarity
- Transaction Timing, Hold Period, and Exit Planning
- Entity Structuring and Ownership Strategy
- Short-Term Rentals, GST/HST, and Compliance Pressure
- A Practical Framework for Smarter Real Estate Tax Strategy
- Final Thoughts: The Best Investors Think in After-Tax Terms
In Canada and across North America, real estate taxation affects every stage of the investment lifecycle, from acquisition and financing through renovation, holding, and eventual sale. It also affects how lenders assess investor cash flow because after-tax income shapes debt service capacity. The strongest portfolios are rarely built on headline appreciation alone. They are built on disciplined after-tax decision making.
This is especially relevant in today’s policy environment. Canada has tightened compliance around real estate reporting, confirmed that the principal residence exemption remains available for qualifying homes, and introduced 2024 capital gains changes that narrow some of the tax advantage relative to ordinary income while preserving the exemption for a principal residence. At the same time, governments continue to use housing taxes, vacancy measures, and targeted rebates to influence supply and investor behavior. These are not marginal developments. They are market signals.
For investors, the practical question is simple. How do you structure and manage real estate in a way that protects cash flow today while preserving flexibility and minimizing tax friction later? The answer begins with understanding the core tax buckets that apply to property ownership and then translating those rules into strategy. That means knowing the difference between current expenses and capital expenses, the distinction between capital gains and business income, the limits around losses, the implications of mixed personal and rental use, and the opportunities created by available rebates and incentives.
This article provides that framework. It is designed as a high-level briefing for investors who want clear, actionable guidance on how real estate taxation shapes returns. The goal is not to encourage aggressive tax positions. The goal is to help you invest with better foresight, stronger documentation, and a more precise understanding of after-tax performance.
Why Real Estate Taxation Matters More Than Most Investors Realize
Taxes influence real estate outcomes in both visible and less obvious ways. The visible impact is the annual bill tied to rental income, property ownership, or a sale. The less obvious impact is the way tax rules change investor behavior. A high recurring property tax can weaken long-term cash flow. A favorable capital gains regime can encourage longer hold periods. A deduction for qualifying expenses can make active property management more attractive than passive ownership. Once you see taxation as a strategic variable, not just a compliance variable, investment analysis becomes more complete.
OECD research has consistently highlighted that recurrent taxes on immovable property tend to be less distortive than transaction taxes. That matters because investors often focus heavily on purchase and sale costs while underestimating how annual carrying costs affect long-term performance. Property taxes, vacancy taxes, and local housing levies can materially change the economics of a deal over a ten-year hold. Markets with lower transfer friction but high recurring costs may reward a different operating strategy than markets with modest annual costs but heavy transaction taxes.
Taxation also affects capital allocation across asset classes. Owner-occupied housing often receives more favorable treatment than other investments, particularly where principal residence exemptions or home-sale exclusions exist. That creates an uneven playing field between personal-use property and income-producing property. Investors who ignore those differences may overestimate the attractiveness of a rental conversion or underestimate the opportunity cost of using capital in a property that does not generate tax-efficient returns.
The practical takeaway is straightforward. Every real estate acquisition should be underwritten on an after-tax basis. That means modeling recurring taxes, deductible operating costs, depreciation or capital cost allowance where relevant, potential loss limitations, and the likely tax treatment on disposition. If you cannot estimate after-tax cash flow and after-tax proceeds, you do not yet know the true investment case.
The Core Taxes Real Estate Investors Need to Understand
Property Taxes and Carrying Costs
Property taxes are one of the most consistent cost items in real estate ownership. Unlike some taxes that arise only on sale or during a profitable year, property taxes apply regardless of whether the property is producing a strong return. For investors, that makes them a direct pressure point on net operating income and debt coverage. In high-tax municipalities, a property that appears attractive based on gross rent can become much less compelling once local tax assessments are accounted for.
Because property taxes are recurring, they should be modeled conservatively. Investors sometimes rely on current tax bills without considering reassessment risk, municipal budget pressure, or rising property values that can increase the tax base. This is particularly important when acquiring underperforming assets that may be reassessed after renovation or stabilization. A better building can produce better rent, but it can also attract a higher tax burden over time.
Property taxes also intersect with tenant strategy. In some markets, the ability to pass through certain costs, either directly or indirectly through rent levels, is constrained by regulation and competitive conditions. That means recurring tax increases may fall largely on the owner. In this sense, property tax exposure is not just a budget item. It is a pricing risk and a margin risk.
Rental Income Taxation
In Canada, rental income must be reported, and many related expenses are generally deductible. This is one of the most important starting points for investors because net rental income, not gross rent, is what drives taxable results. Eligible expenses can include items such as repairs, insurance, utilities, property management fees, advertising, and in many cases interest on money borrowed for the rental property. The ability to deduct legitimate operating costs is essential to preserving current cash flow.
However, not all expenses are treated the same way. Tax rules distinguish between current expenses and capital expenses. Current expenses are typically those that maintain the property and are consumed within the year, while capital expenses usually create a lasting improvement or acquire a durable asset. The distinction matters because current expenses are generally deducted in the current period, while capital expenses are usually added to the cost base and recovered over time, if at all, through depreciation or capital cost allowance rules.
This classification can materially change returns. A repair program that is deductible today improves immediate tax efficiency. A renovation program that must be capitalized may enhance long-term value, but it delays tax relief. Sophisticated investors understand this and phase projects accordingly. They also maintain clean records to support the treatment of each cost because poor documentation can undermine even a legitimate deduction strategy.
Capital Gains on Sale
When an investment property is sold for more than its adjusted cost base and selling expenses, the gain may be taxed as a capital gain unless the facts suggest the activity is better characterized as business income. This distinction is critical. Capital gains often receive more favorable treatment than ordinary business income, which is why investors care deeply about hold period, intent, renovation pattern, financing structure, and the broader facts around the acquisition and sale.
Recent Canadian policy changes in 2024 have increased the taxation of certain capital gains above the annual threshold while preserving the principal residence exemption. For investors, that means gains remain preferable to fully taxed business income, but the gap has narrowed in some circumstances. That does not eliminate the appeal of appreciation. It simply reinforces the importance of planning around timing, ownership, and the expected tax profile at exit.
In the United States, home-sale exclusions for qualifying principal residences are addressed separately from rental property taxation. That separation reflects a broader principle seen across North America. Not all real estate is taxed the same way. The same physical asset can produce very different tax outcomes depending on whether it is used as a home, a rental investment, a short-term accommodation business, or inventory in a profit-making venture.
Current Expenses Versus Capital Expenses: A Small Distinction With Big Consequences
One of the most common tax errors in real estate investing is assuming that every outlay connected to a property can be deducted immediately. In practice, tax authorities draw a clear line between ordinary operating costs and expenditures that improve or extend the useful life of the asset. The difference often comes down to whether the spending restores the property to its previous condition or creates a better asset than the one that existed before.
For example, patching a roof leak may look like a repair, while replacing an entire roof may look more like a capital improvement. Repainting a unit between tenants may be a current expense, while a comprehensive interior redesign tied to repositioning the asset may push costs toward capital treatment. The tax outcome affects short-term cash flow because current deductions reduce taxable income now, while capitalized costs are recovered later and often more slowly.
Investors should not treat this as a technical footnote. The repair versus improvement distinction changes renovation strategy. If your business plan relies on front-loaded tax relief, you need to understand which line items are likely to qualify as current expenses and which will not. It also changes budgeting. A capital-heavy repositioning plan may deliver stronger rents and appreciation, but the tax cash flow profile can be less favorable in the early years.
A disciplined investor keeps invoices, scope descriptions, before-and-after records, financing documents, and contractor contracts organized from day one. Tax planning is much easier when documentation supports the business purpose and the nature of each expenditure. In real estate, record keeping is not clerical. It is strategic evidence.
Depreciation and Capital Cost Allowance: Useful Today, Important Tomorrow
Canada allows capital cost allowance, often referred to as CCA, on qualifying rental property in order to recover part of the building cost over time. In the United States, depreciation serves a broadly similar economic function for rental property. These tools can be valuable because they reduce taxable income without requiring a current cash outlay. For investors who prioritize near-term cash flow, that can improve the annual after-tax return and create more liquidity for debt reduction, reserves, or reinvestment.
Yet this is where short-term optimization can create longer-term complexity. Claiming CCA or depreciation can affect the tax picture on sale and can complicate principal residence treatment if the property is also used as a home. In Canada, where a property is used partly for income production, the principal residence exemption may be reduced or made more complex, especially when CCA has been claimed or when the income-producing use is more than merely ancillary. This is one of the clearest examples of why real estate tax planning has to be lifecycle based rather than year by year.
Investors should also remember that aggressive use of depreciation does not eliminate tax. It often defers it, changes its character, or introduces recapture risk later. That does not mean depreciation is a mistake. It means the benefit should be assessed against the likely hold period, expected appreciation, mixed-use plans, and exit strategy. A deduction that looks attractive in year one may not be attractive if it erodes flexibility in year eight.
The strategic question is not simply whether you can claim depreciation or CCA. The better question is whether claiming it supports the broader objective of the asset. If the property is intended as a pure rental investment with no personal use and a well-defined hold period, the answer may be yes. If the property sits in a mixed personal and investment context, caution is often warranted.
The Principal Residence Exemption and Why Investors Must Treat It Carefully
The principal residence exemption remains one of the most important tax advantages available to Canadian homeowners. If a property was solely your principal residence for every year you owned it, the capital gain is generally exempt. That benefit is significant because it allows substantial appreciation to pass without the capital gains treatment that would otherwise apply. For owner-occupiers, that can be a major driver of household wealth accumulation.
However, two points are frequently misunderstood. First, in Canada, for 2016 and later tax years, the sale must still be reported and the property designated to claim the exemption. The idea that a principal residence sale never needs to be disclosed is simply wrong. Failure to report correctly can jeopardize the exemption and create unnecessary friction with the tax authority. Compliance matters even when the end result is no tax.
Second, a property does not automatically preserve full principal residence treatment if it is partly used to generate income. Renting out a portion of the home, operating a short-term rental, or changing the use of the property can complicate the exemption. The degree of impact depends on the facts, including whether the income use was ancillary, whether structural changes were made, and whether CCA was claimed. Investors who casually convert part of a residence into an income stream without understanding the tax implications can create an avoidable future problem.
This matters because many modern investors move fluidly between personal and investment use. They may live in a property first, rent it later, or buy a larger home and retain the original residence as a rental. These are sensible wealth-building moves, but they require planning. Before changing the use of a property, investors should assess how the shift affects adjusted cost base, future gain allocation, reporting obligations, and the continued availability of the principal residence exemption.
Key investor principle: A tax benefit is most valuable when it is preserved intentionally. Principal residence treatment should never be assumed once a property begins producing income.
Capital Gain or Business Income: The Classification That Can Redefine Profit
One of the most consequential tax questions in real estate is whether profit on sale should be taxed as a capital gain or as business income. In Canada, a property can move from capital treatment to business income treatment if the facts suggest the owner is engaged in a profit-making business rather than holding a passive investment. This is not decided by labels alone. It is determined by the pattern of behavior, the purpose of acquisition, the nature of improvements, the frequency of transactions, and the intent that can be inferred from the evidence.
An investor who buys a rental property, leases it steadily, manages it for cash flow, and sells years later after ordinary appreciation usually presents a different profile than a buyer who acquires distressed homes, renovates aggressively, and resells them quickly. Both are involved in real estate. The tax treatment may be very different. Business income can be taxed less favorably than capital gains, which means the classification can meaningfully reduce after-tax profit.
This is why strategy and documentation must align. If your objective is long-term investment treatment, your financing, operating history, leasing conduct, and disposition pattern should support that reality. If you are effectively conducting a flipping business, the correct strategy is not to pretend otherwise. It is to budget for that tax profile, structure accordingly, and price projects with the proper margin expectations.
Investors should also be careful with short-term rentals and high-touch operating models. In some cases, increased services and active management can change the character of the income or increase compliance obligations. The more a property behaves like an operating business rather than a passive lease asset, the more important classification and reporting become.
Common Myths That Lead to Costly Mistakes
Tax misunderstandings are common in real estate because property sits at the intersection of personal finance, business income, and capital appreciation. The result is that many investors rely on rules that are partly remembered, overly generalized, or flatly incorrect. The consequences are often expensive because they affect not only tax paid, but also transaction timing, financing strategy, and audit risk.
-
Myth one: all mortgage interest and property taxes are always deductible. In reality, deductibility depends on the use of the property, the purpose of the borrowing, and the applicable rules in the relevant jurisdiction. In Canada, the CRA states that in certain contexts you cannot create or increase a rental loss, or reduce other sources of income, by claiming a deduction for interest or property taxes. The facts matter.
-
Myth two: a principal residence sale never needs to be reported. In Canada, dispositions from 2016 onward must be reported and the property designated to preserve the exemption. Silence is not compliance.
-
Myth three: losses on a personal home sale are deductible like investment losses. Under U.S. federal tax rules, losses on the sale of personal-use property such as a home are not deductible. Investors should not assume downside protection exists where the law does not provide it.
-
Myth four: claiming depreciation or CCA has no future consequences. These claims can affect sale outcomes, recapture, and principal residence treatment in mixed-use situations. What helps today can cost flexibility later.
-
Myth five: all real estate profit is passive. Depending on the facts, profits can be characterized as business income rather than passive investment income or capital gain. This is especially relevant for high-frequency transactions, value-add flips, and some short-term rental operations.
The best response to these myths is not caution alone. It is precision. Investors who know which questions to ask before buying, renovating, refinancing, or selling tend to preserve more profit and face fewer unpleasant surprises.
Mixed-Use Property: Where Many Investors Lose Clarity
Mixed-use property is increasingly common. A homeowner may rent a basement suite, list a detached unit on a short-term rental platform, or convert a former residence into a full rental after relocating. These moves can be economically intelligent, but they blur the line between personal use and income production. Once that line becomes unclear, tax outcomes become more complex.
In Canada, mixed-use arrangements can affect the principal residence exemption, especially where the income-producing use is not merely ancillary or where CCA has been claimed. The tax authority may look at the percentage of space used to earn income, whether the area was structurally modified, whether the use was continuous, and whether the owner otherwise maintained the character of the property as a residence. A casual approach to these facts can reduce the benefit available on sale.
There is also a planning issue around expenses. Not every expense applies equally to personal and rental portions of a property. Some costs may need to be allocated based on area, use, or another reasonable method. Investors who fail to separate personal and income-related costs can either overclaim deductions or underclaim legitimate ones. Neither outcome is desirable.
The strategic approach is to define the property’s role clearly. Is it primarily a home with incidental income, a true rental with limited personal use, or a transitional asset moving from one category to another? Once that is established, records, deductions, and future exit planning can be aligned with the actual use.
Transaction Timing, Hold Period, and Exit Planning
Taxes do not arise only because a gain exists. They arise because a gain is realized within a specific structure and at a specific time. That means timing is one of the few variables investors can often influence directly. Selling before year-end, after year-end, before a use change, after a renovation cycle, or in a year with lower overall income can all affect after-tax results depending on the jurisdiction and the broader tax profile of the investor.
Hold period matters because it shapes both tax characterization and economics. A short hold may support a stronger annualized return if the market rises quickly, but it can also increase the likelihood that profit looks like business income rather than long-term investment appreciation. A longer hold can strengthen the investment narrative, allow property taxes and transaction costs to be amortized over more years, and create more room for rent growth. Tax strategy should therefore be part of the hold versus sell analysis, not something considered only after a buyer is found.
Exit planning should begin at acquisition. Investors should ask what the likely tax treatment will be on sale, what documentation will support that position, whether depreciation or CCA claims are worth the future consequences, and how any principal residence considerations may evolve if use changes. Good exits are usually designed early. Poor exits are often improvised.
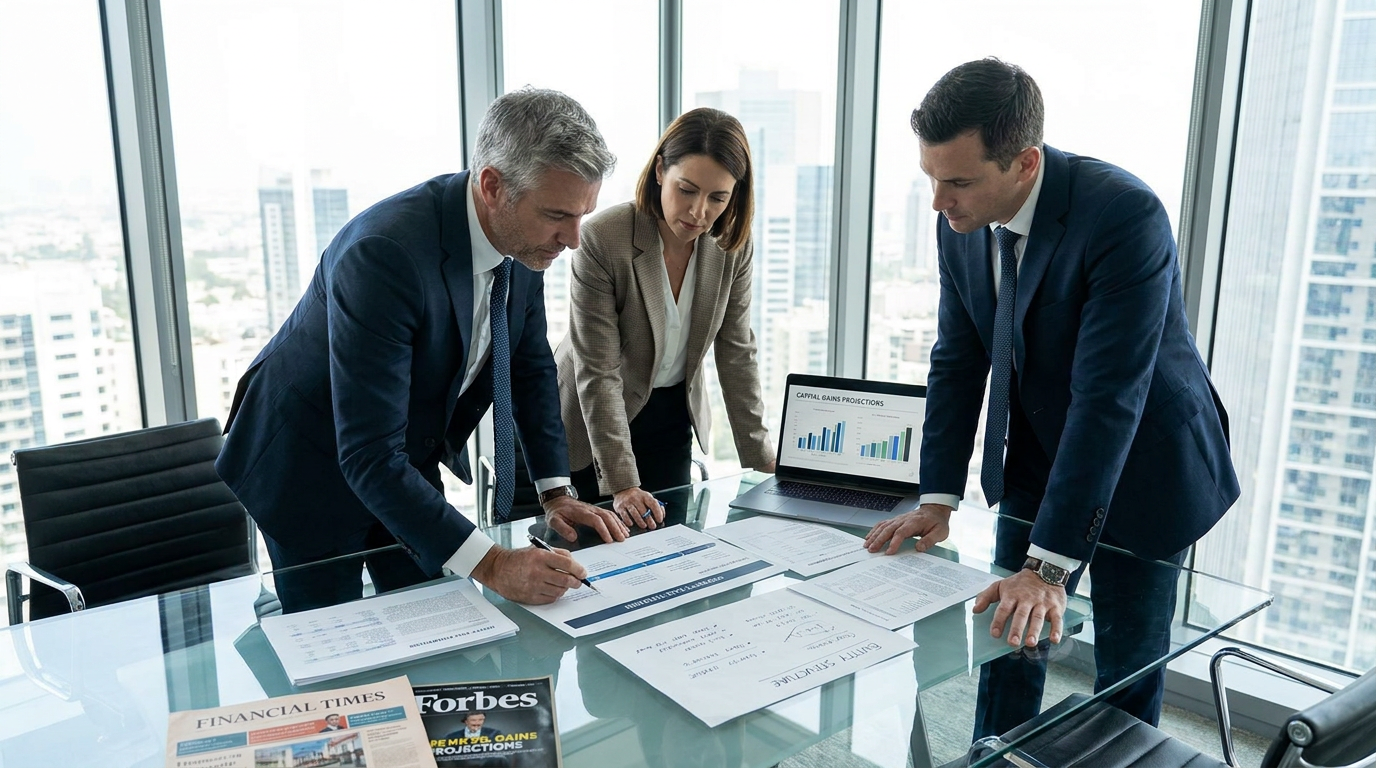
Entity Structuring and Ownership Strategy
Another major strategic lever is deciding whether to hold real estate personally or through an entity. The right answer depends on scale, financing goals, liability considerations, administrative capacity, local tax rules, and the investor’s broader income profile. There is no universal best structure. There is only a structure that best fits the asset and the investor’s objectives.
Personal ownership can be simpler and may align naturally with certain financing options, especially for smaller investors and residential properties. Entity ownership may offer operational advantages, clearer separation between assets, and strategic flexibility in some contexts. However, complexity should not be added without reason. More structure is only better if it improves risk management, tax efficiency, or execution enough to justify the cost.
Investors should be especially careful not to let tax considerations dominate every structuring decision in isolation. Financing terms, lender preferences, estate planning, co-investor arrangements, and operational control all matter. The right ownership model is usually the one that balances these factors while preserving a sensible after-tax outcome. Good tax planning supports the business plan. It does not replace it.
Short-Term Rentals, GST/HST, and Compliance Pressure
Real estate tax planning has become more demanding as governments increase enforcement and refine policy around housing supply and commercial use. In Canada, compliance in the real estate sector has tightened, with mandatory reporting of property sales and increased attention to non-compliance, short-term rentals, and GST or HST issues. Investors operating in these segments should expect more scrutiny, not less.
Short-term rental activity can raise both income tax and indirect tax questions. Depending on the nature of the operation, the property may begin to resemble a hospitality business rather than a passive rental. That can affect reporting, deductions, and potentially the characterization of income. Investors drawn to short-term rentals for yield should factor in the administrative burden and regulatory risk alongside gross revenue potential.
There are also opportunities on the incentive side. New residential rental projects in Canada may qualify for GST or HST new residential rental property rebates. Federal and provincial policy has increasingly signaled support for purpose-built rental housing, including temporary relief measures tied to Ontario for 2026. For developers and larger investors, these incentives can materially improve project economics. But they are only useful if identified early and integrated into the capital stack and development timeline.
The broader lesson is that compliance and incentives are two sides of the same policy coin. Governments are using tax tools to discourage certain behavior and encourage other forms of housing activity. Smart investors watch both directions carefully.
A Practical Framework for Smarter Real Estate Tax Strategy
Tax strategy does not need to be aggressive to be effective. In most cases, strong outcomes come from disciplined planning, accurate classification, and timely reporting. Investors who routinely outperform on an after-tax basis usually follow a repeatable process.
-
Underwrite after-tax, not pre-tax. Model rental income, property taxes, deductible costs, financing interest treatment, depreciation or CCA options, and expected disposition tax before you buy.
-
Define the property’s role clearly. Decide whether the asset is a principal residence, a long-term rental, a redevelopment play, a flip, or a mixed-use property. Tax treatment follows facts, not marketing language.
-
Track capital and current expenditures separately. This improves tax accuracy and helps you evaluate renovation plans with a clearer view of near-term cash flow impact.
-
Be cautious with depreciation and CCA in mixed-use scenarios. The current-year benefit may be outweighed by later complications, especially where principal residence treatment could matter.
-
Plan the sale early. Consider hold period, gain profile, reporting requirements, and the likely tax characterization long before you list the asset.
-
Document everything. Purchase records, invoices, lease agreements, financing use, property-use changes, and sale costs all support a more defendable tax outcome.
-
Review incentives and indirect taxes. GST or HST rebates, local vacancy taxes, land transfer taxes, and municipal rules can change economics significantly.
What distinguishes experienced investors is not that they avoid tax entirely. It is that they understand where tax enters the investment equation and respond before it becomes a problem. That is a far more durable advantage than chasing one-off deductions.
Final Thoughts: The Best Investors Think in After-Tax Terms
Real estate rewards patience, judgment, and disciplined execution. Taxation touches all three. It determines how much rent becomes usable cash flow, whether renovations create immediate deductions or long-term basis, whether a sale is treated as a capital gain or business income, and whether a home can truly be sold tax free under principal residence rules. In a market where margins can compress quickly, these distinctions are not technical trivia. They are drivers of net return.
The smartest investors do not ask only whether a property will appreciate or whether the rent will cover the mortgage. They ask how the asset will perform after tax under realistic assumptions. They think about reporting obligations before closing, not after receiving a notice. They understand that claiming every available deduction is not always the same as maximizing long-term wealth. Often, preserving flexibility and protecting future treatment is worth more than squeezing out a small current-year benefit.
As policy evolves across Canada and North America, this mindset becomes even more important. Capital gains rules are changing, compliance is tightening, incentives are shifting toward rental supply, and housing taxes continue to shape investor behavior. The advantage belongs to those who treat taxation as part of strategy from the beginning.
If there is one principle to carry forward, it is this: real estate should be evaluated on the return you keep, not the return you project before tax. Once investors adopt that standard, better decisions tend to follow naturally.

No Comment! Be the first one.