Canada’s Housing Slowdown Signals a Repricing of Risk for Investors
Every cycle sends a signal before it sends a headline. This month, the signal is a quiet one: Canadian home sales slipped 0.7 percent from July, according to the Canadian Real Estate Association, and are down 6.9 percent from a year ago. For investors accustomed to reading price alone, that is not the number that matters most. The number that matters is the sales-to-new-listings ratio, which fell to 49.1 percent from 51.1 percent, well below its long-term average of 54.7 percent. Supply is now outpacing demand, and that shift changes the calculus for anyone holding or considering residential property in this market.
New listings rose 3.3 percent from July, ending a three-month decline. On its own, more inventory sounds like a healthy correction. Paired with softening demand, though, it points to a market where sellers are losing pricing power. The CREA Home Price Index held flat month over month but remains 3 percent below where it stood a year ago. That is a market searching for a floor, not one preparing to bounce.
The more consequential story for portfolio decisions is on the financing side. CREA senior economist Shaun Cathcart pointed to a Bank of Canada warning on rising inflation risk and questions about the durability of recent growth as the real driver of the shift. Fixed mortgage rates have already moved higher on rising bond yields, and variable-rate borrowers are now pricing in the possibility of a hike rather than a cut. Markets are assigning roughly a 60 percent probability to a Bank of Canada rate increase as early as October, from a current benchmark of 2.25 percent, with about 1.25 percentage points of tightening priced in by the end of 2027.
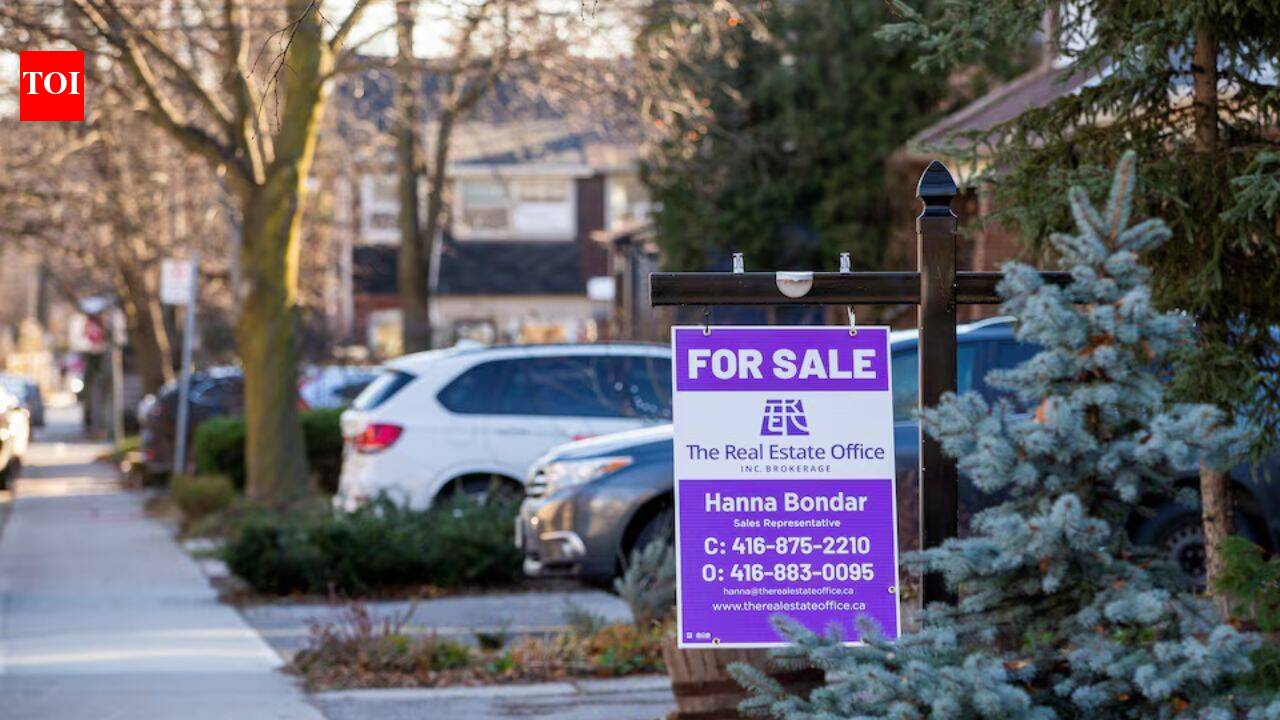
Fixed mortgage rates have already increased on higher bond yields, and a Bank of Canada rate hike has returned to market expectations for variable-rate borrowers.
For investors, this combination of falling sales, flat-to-soft pricing, rising inventory, and a hawkish rate outlook is not a reason to panic, but it is a reason to recalibrate timing. Leverage that looked comfortable at 2.25 percent benchmark rates may not look comfortable if tightening resumes into 2027. Cap rate assumptions built during a period of anticipated rate cuts need to be revisited now that the direction of travel has reversed. Energy-driven inflation tied to the Middle East conflict is part of what is pushing bond yields higher, a reminder that housing markets do not move in isolation from global macro forces.
The opportunity here is not obvious, and that is exactly the point. Markets that are repricing risk, rather than trending cleanly in one direction, tend to punish investors who assume the recent past will repeat. Patient capital that waits for clarity on rates, and that stress tests deals against a higher-for-longer scenario rather than the rate cuts many expected earlier this year, will be better positioned than capital chasing the last cycle’s assumptions. Canada’s housing market is not collapsing. It is recalibrating, and recalibration rewards discipline over speed.
Source: Times of India