What August’s Softening Housing Starts Signal for Real Estate Investors
Every investor worth their salt watches supply before they watch price. The latest data from Canada Mortgage and Housing Corp. gives us a fresh read on that supply pipeline, and it is worth pausing on. The seasonally adjusted annual rate of housing starts came in at 229,046 units for August, a slight step down from July’s 229,360. On its own, that is a modest move. In context, it tells a more useful story about where the market is heading.
Actual monthly starts in centres with populations of 10,000 or more totalled 17,691 in August, down from 18,112 a year earlier. Rural starts held at an estimated 11,224 units annualized. The six-month moving average, which smooths out the noise and gives a cleaner read on trend, came in at 244,149 units for all areas of Canada, down 1.3 per cent from July. That moving average is the number I pay closest attention to. Monthly figures jump around. Trend lines do not lie as easily.
CMHC deputy chief economist Kevin Hughes pointed to a regional split behind the national figure. Modest gains in Quebec and Alberta were not enough to offset a decline elsewhere, with Ontario cited as the most notable drag. That divergence matters more to allocators than the headline number does. A national average can mask meaningfully different conditions on the ground, and right now the ground looks uneven.
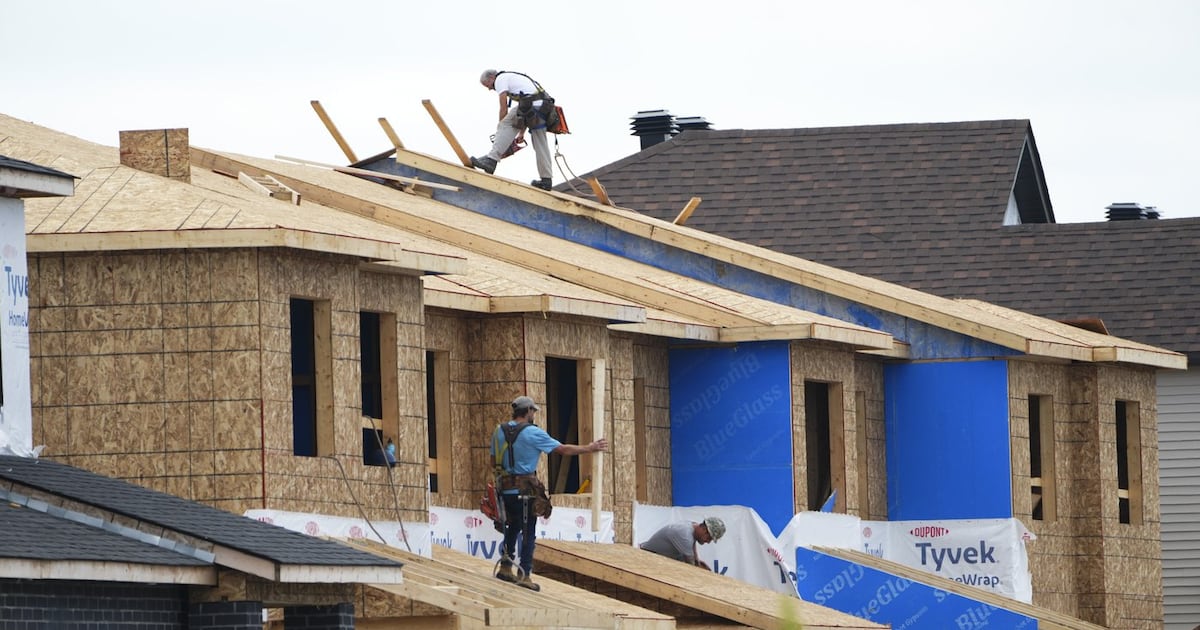
For investors, a slowing pace of new construction is rarely a red flag on its own. It is a signal to look one layer deeper. When starts trend down in a market like Ontario while demand fundamentals stay intact, the arithmetic tends to favour existing inventory and completed rental stock over speculative land plays tied to new supply that may take years to reach the market. Alberta and Quebec telling a different story, meanwhile, is exactly the kind of regional divergence that rewards investors who allocate by market rather than by national headline.
A national number tells you where the market has been on average. Regional splits tell you where the opportunity actually sits.
The discipline here is the same one that has always separated durable returns from reactive ones. Starts data is a leading indicator of future supply, and future supply is one of the clearest levers on rental pricing power and long term appreciation. A softening national trend, with Ontario leading the pullback, suggests tighter future supply in that province specifically, which is a variable worth weighing against any assumptions baked into current underwriting. Meanwhile, the relative resilience in Alberta and Quebec is worth watching as those markets continue attracting capital and population.
None of this calls for a dramatic reaction. It calls for attention. A 1.3 per cent dip in the six-month moving average is not a market turning point, it is a data point, and disciplined investors treat it as one input among many. But when the pipeline narrows in one region while it holds elsewhere, that is precisely the kind of divergence that separates the investors reading the signals from the ones only reading the headline.
Source: BNN Bloomberg, reporting on data from Canada Mortgage and Housing Corp.