Canada’s Luxury Market Splits in Two: Where the Smart Money Is Still Moving
Luxury real estate rarely moves as one national story, and the latest numbers out of Canada make that clearer than ever. A fresh RE/MAX Canada report covering the first nine months of 2026 shows seven markets posting sales growth while six others pulled back, a split that tells investors far more about where opportunity sits than any single national average ever could.
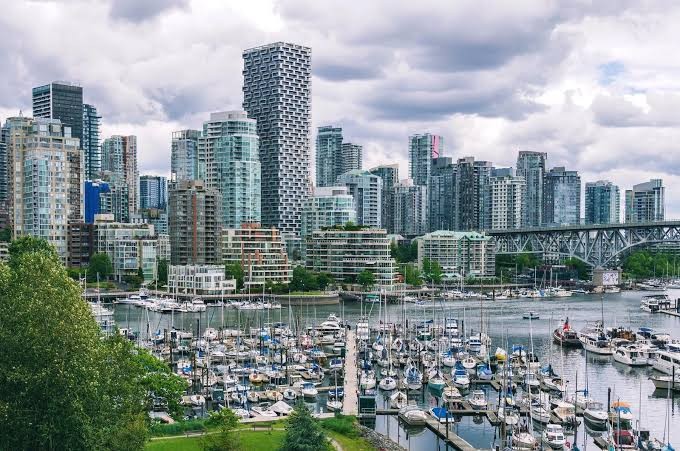
Burlington led every market tracked with a 26.3 percent jump in luxury sales, trailed by St. John’s at 21 percent, Calgary at 20.6 percent, Edmonton at 15.9 percent, and Saskatoon at 15.3 percent. Ottawa and Winnipeg also closed in positive territory, if more modestly. Meanwhile, Greater Vancouver’s ultra-luxury segment, homes starting at 3 million Canadian dollars, slid 17 percent to 594 deals, down from 716 a year earlier. The Greater Toronto Area fell 9.4 percent at the same price threshold, and Oakville dropped 16.7 percent.
For investors, the headline is not that some cities won and others lost. It is why. Calgary and Edmonton classify luxury at lower price points, 1.5 million and 1 million dollars respectively, which means local economic strength and relative affordability are pulling buyers who might once have looked only at Vancouver or Toronto. That is a demand migration story, and demand migration is exactly what disciplined capital should be watching.
What stands out most to me is the detail buried beneath the regional headlines: even in markets posting overall declines, the very top of the market is still accelerating. Properties above 7.5 million dollars in the GTA rose 17.6 percent in sales, and deals above 5 million in Oakville climbed roughly 18 percent. That is not a market in retreat. That is a market where mid-tier luxury buyers are hesitating while the highest-net-worth purchasers keep deploying capital regardless of rate cycles. Recognizing that distinction matters when you are positioning a portfolio, because treating “luxury” as one undifferentiated tier will cause you to misread exactly where the resilience actually lives.
Regional factors have become more important in explaining market movements, and interest rates and supply and demand alone are no longer sufficient to predict sales trends.
That line, attributed to RE/MAX Canada President Don Kotek, should be read as a direct instruction to anyone building a real estate thesis for 2027. The old shorthand of tracking national rate decisions and extrapolating outward no longer explains what is happening on the ground. There is also a timing wrinkle investors need to weigh carefully. This dataset closes on September 30, 2026, which means it predates the Bank of Canada’s October 28 decision to raise its key rate a quarter point to 2.5 percent. RBC’s October figures already show softening sales activity in Calgary, Toronto, and Vancouver alike, suggesting the next RE/MAX read could look noticeably different.
My read for readers positioning capital now: the secondary luxury markets riding local economic tailwinds, Calgary, Edmonton, Burlington, St. John’s, deserve a closer look precisely because they are still under-priced relative to the coastal giants, even as those giants show that ultra-high-end demand hasn’t actually disappeared, it has simply concentrated. The smart move is rarely chasing the loudest headline number. It is understanding which segment of a cooling market is still quietly compounding.