Why Softening Home Prices Could Be the Smartest Signal for Canadian Buyers and Families
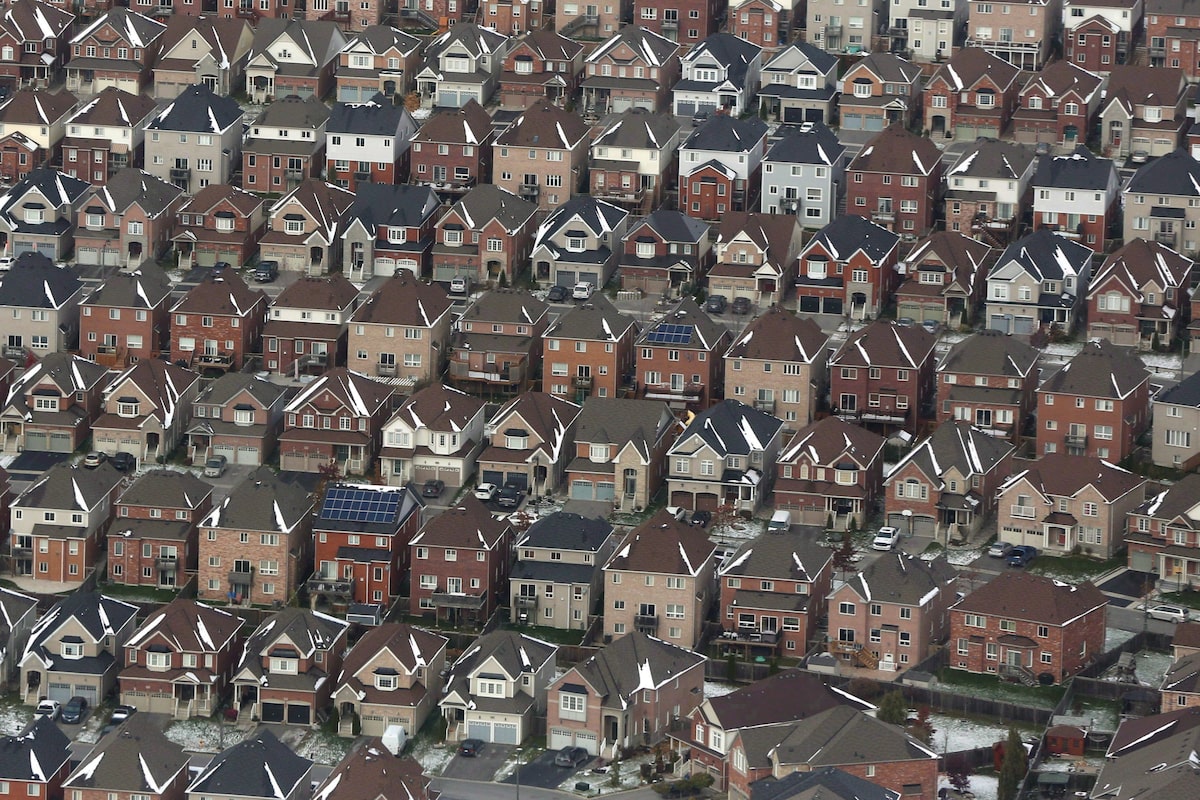
Markets send signals, and the current pullback in Canadian home prices is one worth reading carefully. After a run that produced peak unaffordability between 2020 and 2022, prices have eased in cities like Vancouver, Edmonton, Toronto and Halifax. For investors conditioned to treat rising prices as the only good outcome, that correction can feel uncomfortable. But strip away the emotion and this is a market recalibrating, and recalibration is exactly when opportunity gets created for those positioned to act.
National Bank Financial recently flagged the longest streak of improving housing affordability on record, eleven straight quarters. That is a meaningful data point for anyone building a long term property strategy. At the same time, BMO Economics is right to caution that the market remains unaffordable by historical standards, with a typical mortgage payment plus utilities consuming roughly 41 per cent of income against a long term median of 35 per cent. Last month’s mortgage rate increase, described by NBF as the sharpest in four years, adds friction to that affordability progress. This is the push and pull that defines every real cycle, and it is the backdrop against which serious capital allocation decisions get made.
What stands out most from an investment lens is the intergenerational transfer of capital now underway. In 2024, almost one third of first time homebuyers received parental help toward a down payment, according to CIBC Economics, with an average gift value of 115,000 dollars. That is not a footnote, it is a structural feature of today’s market. Every dollar boomers move from retirement savings into their children’s down payments is a dollar leaving TFSAs, RRSPs and RRIFs and entering the property market through a different door. A moderation in home prices reduces the pressure for that transfer, which has real implications for retirement portfolio planning on one side of the ledger and first time buyer affordability on the other.
The strongest real estate opportunities are rarely found by looking at price alone. They come from understanding demand, timing, location strength, rental movement, and the long term direction of the market.
Context matters here. The national average home price sat at 666,538 dollars in September, compared with 164,454 dollars in 2000, a compound gain of roughly 5.5 per cent a year, more than double the average 2.2 per cent inflation rate over that period. A near term correction does not undo two and a half decades of structural appreciation, and it should not be mistaken for a collapse in long term value. For equity rich owners, a modest pullback trims paper wealth without threatening the underlying position. For buyers priced out during the 2020-22 run, it is the clearest entry signal the market has produced in years.
My read for KG Invest readers is straightforward. Treat this affordability window as a planning opportunity rather than a reason to panic. Younger buyers entering now, even amid higher borrowing costs, are buying closer to fair value than those who transacted at the peak. Owners weighing whether to gift equity to adult children should model both paths, since every dollar kept invested today carries a different compounding outcome than a dollar deployed as a down payment gift. Timing, as always, is the variable that separates a good decision from a lucky one.
Source: The Globe and Mail