Why Canadian Buyers Are Still Sitting on the Sidelines Despite Rate Hike Chatter
In most cycles, the mere whisper of rising borrowing costs is enough to light a fire under hesitant buyers. Pull-ahead demand is a well worn pattern: when rates look set to climb, people who were planning to buy later rush to lock in sooner. This time, that pattern simply is not showing up, and for investors tracking the Canadian housing market, that absence tells its own story.
Phil Soper, president and CEO of Royal LePage, recently told Canadian Mortgage Professional that despite growing talk of Bank of Canada rate hikes and a notable jump in fixed-rate mortgages south of the border, transaction volumes in Canada remain flat. No surge, no rush, no sideline exodus. Soper pointed to a combination of trade war anxiety and persistent inflation concern as the forces keeping would-be buyers frozen in place, even when a financial incentive to act now is staring them in the face.
That is the signal worth sitting with. Markets do not go flat because fundamentals are bad. They go flat because confidence is missing, and confidence is a far harder thing to price than a mortgage rate.
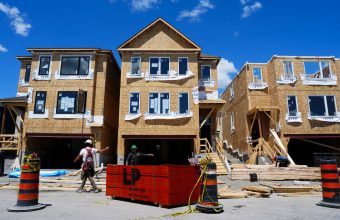
Royal LePage has already adjusted its expectations accordingly. The firm’s second-quarter house price survey originally projected 2 percent national price growth by the fourth quarter of 2026. That forecast has now been cut in half, to a more modest 1 percent, reflecting what Soper describes as a deep freeze still gripping the market. Toronto and Vancouver, two of the country’s bellwether markets, continued to see prices slide through the second quarter. Montreal was the notable exception, bucking the national trend and reminding investors that this is not a uniform story across every region.
Even an incentive like that is not enough to get people off the sidelines if they’re feeling very uncomfortable.
For investors, this divergence between city performance is where the real opportunity sits. A flat national average hides meaningful variation underneath it. Markets still sliding, like Toronto and Vancouver, may be approaching a point where valuations become more attractive relative to rental demand and long term fundamentals, provided the buyer is prepared to hold through continued softness rather than time a bottom perfectly. Markets bucking the freeze, like Montreal, suggest local demand drivers strong enough to withstand macro hesitation, which is exactly the kind of resilience worth studying before committing capital.
The broader lesson here is about reading sentiment as a market indicator in its own right. Rate anticipation alone is not moving behavior right now, which means the usual playbook of front-running a hike cycle does not apply cleanly this time. Trade policy uncertainty and inflation nerves are doing more to shape buyer psychology than borrowing cost forecasts, and that psychology is unlikely to shift until those broader anxieties ease. Investors who understand this are better positioned than those simply waiting for a rate announcement to tell them when to move.
Patience, in this environment, is not passivity. It is strategy. Watching where regional performance diverges from the national average, and understanding why, will matter more over the next several quarters than any single Bank of Canada decision.
Source: Canadian Mortgage Professional