Why Lenders Are Holding the Line on Condo Financing, and What It Means for the Next Decade of Supply
Every development cycle eventually meets its gatekeeper, and in the Toronto region right now that gatekeeper is the construction lender. Meridian Credit Union, one of the province’s largest providers of condo construction financing, has made it clear it will not loosen the presale threshold that determines whether a project gets built at all. That single number, the familiar 70 per cent of units sold before financing is released, is quietly reshaping the future shape of this region’s skyline.
This is not a story about one lender’s caution. It is a story about what happens to a development pipeline when the buyer base that once fueled it disappears. For years, individual investors carried the preconstruction market, allowing developers to hit sales thresholds quickly and move projects from concept to crane. With those investors largely on the sidelines amid falling resale values, builders are left trying to reach the same finish line with a buyer pool that moves far more slowly and far more cautiously.
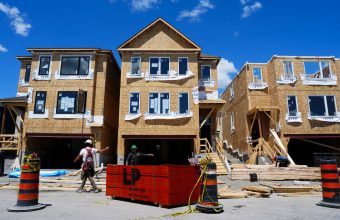
The numbers tell the story plainly. Only four preconstruction launches have occurred so far this year, compared with 101 during the 2021 boom. Condo starts in the first half of the year point toward roughly 8,300 units for 2026, which would be the weakest pace since 1998. The cancellation of the M6 tower in Mississauga, a 58-storey, nearly 900-unit project that was meant to be the sixth phase of a much larger master plan, is a clear signal of what happens when a project cannot clear the sales bar lenders require.
From a development strategy standpoint, this is where timing, risk, and policy collide. Lenders are not being unreasonable when they point out that lowering the threshold in a falling price environment would push more risk onto their own balance sheets, potentially leaving them holding unsold inventory if a developer runs into trouble. With 5,127 newly built units already sitting unsold across Toronto and Hamilton, that concern is not theoretical. But the industry’s counterpoint also deserves weight. If end users, the people who actually intend to live in these homes, prefer to buy later in the construction cycle and need to assemble deposits that now average $164,000 for a 500-square-foot unit, the traditional financing model built around early, heavy presales no longer matches how real buyers behave.
If the threshold is not lowered, I expect new development to remain stalled. Projects will keep getting shelved because they cannot reach the presale level lenders require.
That warning from Urbanation’s Shaun Hildebrand is the kind of statement that should land squarely on the desks of planners and policymakers, not just developers. Every stalled project is a building that will not exist when demand eventually returns, and development timelines do not compress on demand. A tower shelved today does not simply launch next year once sentiment improves. It re-enters a queue of approvals, financing, and construction scheduling that can take years to clear.
What this moment really calls for is a rethink of the financing architecture itself, not just a debate over where to set the threshold. Ideas raised by voices like Zonda Urban’s Jasmine Young, around financing models that do not require buyers to commit so far in advance, point toward the kind of structural innovation this cycle may ultimately demand. For now, the message from lenders is steady and unambiguous: the risk calculus has not changed, even if the market around it has. For anyone thinking about the next decade of housing supply in this region, that steadiness is worth watching closely, because it is currently the single biggest constraint on how many homes get built.
Source: The Globe and Mail