September’s Housing Pullback Is a Signal, Not a Verdict, for Canadian Investors
Four months of quiet progress in Canada’s housing market just hit a wall. New data from RBC Economics shows national resales slipped 2.3% month over month in September, new listings pulled back 1.8%, and the MLS Home Price Index eased 0.4% from August, now sitting 3.5% below where it stood a year ago. For anyone reading the market purely on sentiment, this looks like bad news. For investors who understand how to read a cycle, it is something more useful: information.
What changed was not demand fundamentals. It was risk pricing. Escalating Canada-US trade tensions and shifting Bank of Canada rate expectations converged at the same moment, and buyers did what buyers always do when uncertainty rises faster than conviction: they paused. That is not a structural flaw in the market, it is a timing event, and timing events are exactly where disciplined investors earn their edge.
Shaun Cathcart, senior economist at the Canadian Real Estate Association, framed it plainly. “After a four-month run of modestly positive progress on demand, supply, and prices, many of Canada’s housing markets took a step back in September.” Notice the language. A step back, not a reversal. The momentum that built through the summer did not evaporate, it stalled while the market waits for clarity on tariffs and borrowing costs.
For investors, a softening price index paired with tighter new listings is worth watching closely. Fewer new listings alongside falling resales suggests sellers are also choosing to wait rather than chase a softer market, which tends to limit how far prices can realistically fall. That combination, buyers hesitant and sellers unwilling to concede too much, often produces a narrower, more negotiable window rather than a true downturn. Those windows do not stay open long once rate expectations settle.
After a four-month run of modestly positive progress on demand, supply, and prices, many of Canada’s housing markets took a step back in September.
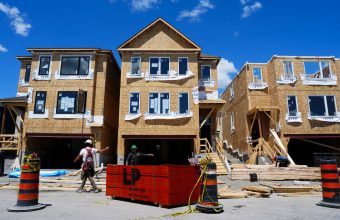
The trade tension variable deserves particular attention. Tariff uncertainty does not just affect sentiment, it affects construction costs, materials pricing, and ultimately new supply timelines, which feeds back into rental demand and long term value in markets where inventory is already tight. Investors with a multi-year horizon should be watching how long this uncertainty persists more than they watch any single month’s index number.
None of this calls for urgency. It calls for positioning. A market pausing on rate expectations is a market that rewards patience and punishes overleveraged speculation. Investors who keep their financing flexible, watch the Bank of Canada’s next moves closely, and resist reading one soft month as a trend will likely be the ones best placed once demand, supply, and prices resume the progress Cathcart described before September’s interruption.