Canada’s Housing Math Doesn’t Add Up: Why the Supply Gap Is a Development Problem, Not a Demand Problem
Every so often a number comes along that reframes an entire conversation. This time it is 2.4 million. That is the shortfall CMHC now projects if Canada continues building at its current pace instead of closing the gap between what the country needs and what it is actually producing. For anyone who thinks about land, timing, and long term city growth for a living, this is not a headline to skim past. It is a signal about where the next decade of development risk and opportunity will concentrate.
According to CMHC’s fall 2026 Housing Supply Report, Canada needs somewhere between 417,000 and 469,000 new units a year through 2036 to bring affordability back toward pre-pandemic levels. The country is currently tracking toward roughly 231,000 annually. That is not a modest miss. It is a structural gap that persists even as population growth has slowed and market demand has temporarily softened. The report’s most important insight is not the size of the shortfall itself, but the fact that it is barely moving despite a cooling market. Demand eased. Supply eased faster.
That distinction matters enormously for anyone involved in land strategy and project feasibility. A softer market usually looks like an opportunity to pause. CMHC’s Deputy Chief Economist, Aled ab Iorwerth, put the risk plainly, warning that Canada could underbuild during this quieter window and find itself even further behind once demand strengthens again. In development terms, this is the classic mistake of reading a temporary lull as a long term signal, then discovering the pipeline cannot be turned back on fast enough when momentum returns.
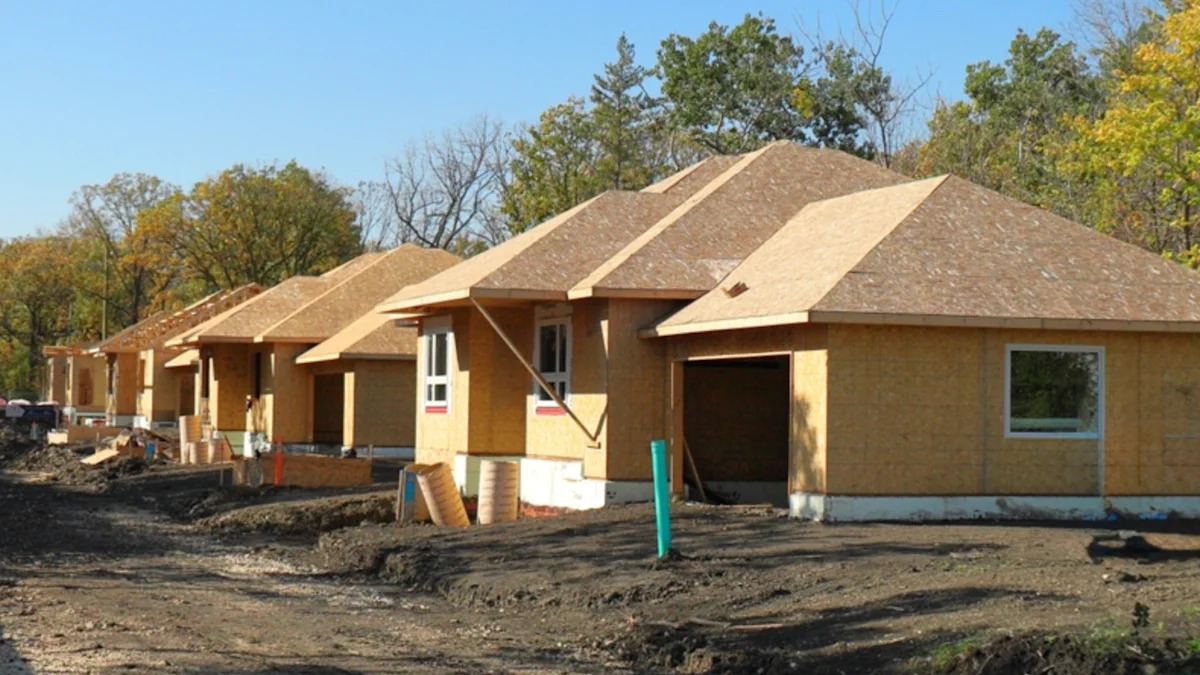
The regional picture is where this becomes a strategy conversation rather than a national abstraction. Toronto still needs to lift annual housing starts by at least fifty percent over the coming decade, even as condo presale activity stalls. Vancouver’s gap has held steady, propped up by purpose built rental now accounting for nearly sixty percent of starts, but its collapsing condominium pipeline threatens the ownership market that anchors long term community stability. Montreal and Ottawa are both losing ground, skewed heavily toward rental with ownership construction near multi year lows. Calgary, by contrast, is narrowing its gap through near record construction activity, and Edmonton stands out as the only major market without a structural supply gap at all, a result of construction consistently keeping pace with population growth.
The key risk now is that Canada underbuilds during this softer market and finds itself further short of housing when demand strengthens again.
What Edmonton and Calgary demonstrate, and what Toronto and Vancouver are struggling with, is that supply gaps are not simply a function of demand pressure. They are a function of whether construction capacity, financing conditions, and municipal approvals stay aligned even when the market gets quiet. High borrowing costs, elevated construction expenses, and difficult presale financing are the practical forces stalling projects right now, and CMHC’s own data shows housing starts down four percent through the first seven months of the year compared to 2025.
For anyone shaping large scale housing vision, the lesson from this report is straightforward. Land decisions made today, on financing structure, on unit mix, on which markets keep moving through a soft cycle, will determine who is positioned to deliver when demand inevitably returns. The gap will not close itself, and the cities that keep building through the quiet will be the ones best positioned for the next decade.
Source: Money.ca via Yahoo Finance