The renewal wave deserves particular attention from anyone holding leveraged property. Roughly 12 percent of outstanding Canadian mortgages, the last cohort of pandemic-era five-year fixed terms, will renew over the next year. The Bank’s own Financial Stability Report projects payments on these loans rising about 15 percent on average, meaning a $2,000 monthly payment could climb toward $2,300. That is a real cash flow event for landlords and owner-investors alike, and it should be modeled now, not discovered at the renewal letter. There is a workaround worth knowing: OSFI does not expect lenders to apply the stress test to uninsured borrowers who switch lenders at renewal without increasing their loan amount, which opens genuine room to shop rates rather than accept a renewal offer passively.
Table Of Content
- Rate Cuts Won’t Save Affordability: What the BoC’s Blunt-Tool Admission Means for Your Property Strategy
- Rate Cuts Won’t Save Affordability: What the BoC’s Blunt-Tool Admission Means for Your Property Strategy
- Rate Cuts Won’t Save Affordability: What the BoC’s Blunt-Tool Admission Means for Your Property Strategy
- Rate Cuts Won’t Save Affordability: What the BoC’s Blunt-Tool Admission Means for Your Property Strategy
- Rate Cuts Won’t Save Affordability: What the BoC’s Blunt-Tool Admission Means for Your Property Strategy
- Rate Cuts Won’t Save Affordability: What the BoC’s Blunt-Tool Admission Means for Your Property Strategy
- Rate Cuts Won’t Save Affordability: What the BoC’s Blunt-Tool Admission Means for Your Property Strategy
Rising prices made housing less affordable, but they also supported household wealth and economic growth.
That tension, between affordability and the household wealth built into home equity, is the real investment signal here. Rogers herself warned that falling prices would reduce household wealth and stress borrowers and lenders, which tells you the Bank has little appetite for engineering a price correction. For investors, that reads as a floor under values even amid soft sales. The strategy that follows is not about predicting the next rate decision on October 28. It is about underwriting deals at today’s stress-test rate, stress testing your own renewals against a 15 percent payment increase, and recognizing that in a market where policy cannot move the real constraint, supply and location fundamentals matter more than ever.
Source: Yahoo Finance / Money.ca
Rogers made the mechanics clear. The Bank sets one rate for the entire economy. It cannot build homes, rezone land, or speed up permits. Cut the rate and more buyers qualify, but with supply still constrained, prices simply absorb the extra demand. Raise it and affordability on paper improves while fewer households can actually borrow. Either direction, the lever does not reach the root problem, which is supply. For investors, this is not a bearish signal. It is clarity. If you have been waiting for a dramatic rate drop to unlock cheaper financing and a buyer’s market at the same time, Rogers just told you that combination is unlikely to arrive.
Consider the numbers already on the board. The national average home price sat at $668,219 in August, up only 0.6 percent year over year, even as sales volume fell 6.9 percent. That is a market cooling in transaction activity while holding its price floor, a pattern that rewards patient capital over opportunistic timing. Desjardins expects the policy rate, currently held at 2.25 percent, to stay flat through year end before rising half a point in the first half of 2027. That is not the setup for a rush of cheap leverage. It is a setup for disciplined underwriting.
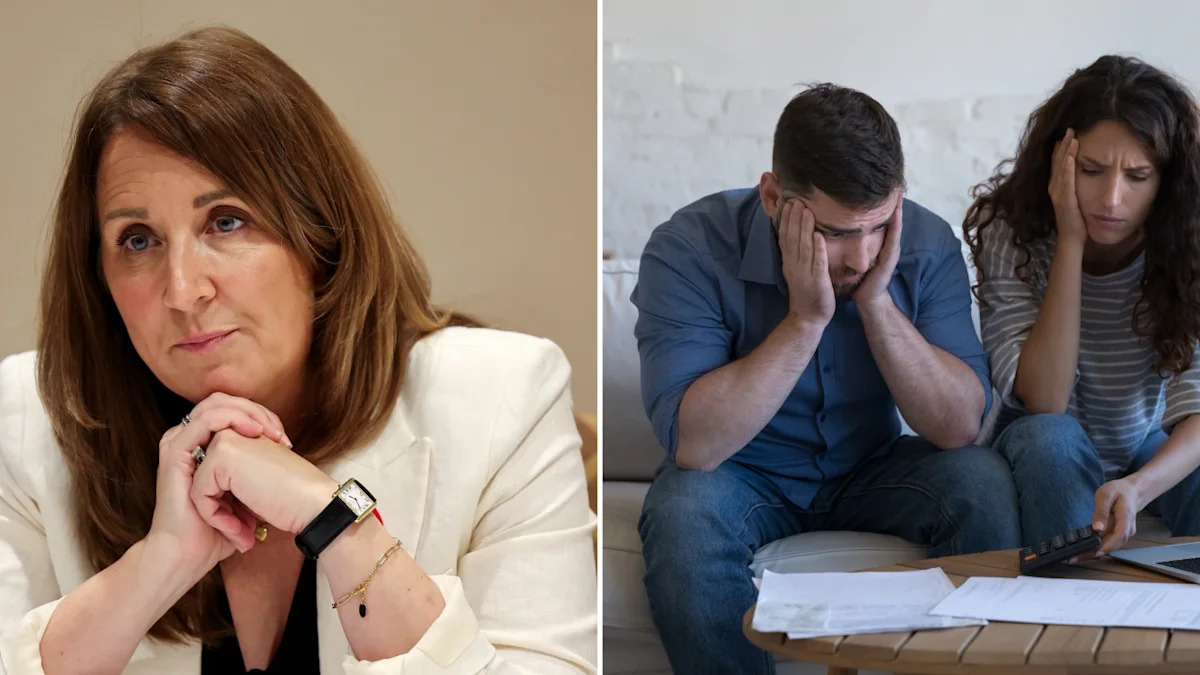
The renewal wave deserves particular attention from anyone holding leveraged property. Roughly 12 percent of outstanding Canadian mortgages, the last cohort of pandemic-era five-year fixed terms, will renew over the next year. The Bank’s own Financial Stability Report projects payments on these loans rising about 15 percent on average, meaning a $2,000 monthly payment could climb toward $2,300. That is a real cash flow event for landlords and owner-investors alike, and it should be modeled now, not discovered at the renewal letter. There is a workaround worth knowing: OSFI does not expect lenders to apply the stress test to uninsured borrowers who switch lenders at renewal without increasing their loan amount, which opens genuine room to shop rates rather than accept a renewal offer passively.
Rising prices made housing less affordable, but they also supported household wealth and economic growth.
That tension, between affordability and the household wealth built into home equity, is the real investment signal here. Rogers herself warned that falling prices would reduce household wealth and stress borrowers and lenders, which tells you the Bank has little appetite for engineering a price correction. For investors, that reads as a floor under values even amid soft sales. The strategy that follows is not about predicting the next rate decision on October 28. It is about underwriting deals at today’s stress-test rate, stress testing your own renewals against a 15 percent payment increase, and recognizing that in a market where policy cannot move the real constraint, supply and location fundamentals matter more than ever.
Source: Yahoo Finance / Money.ca
When the second most powerful voice at the Bank of Canada tells you not to count on interest rates to fix housing, you listen, and more importantly, you reposition. Senior Deputy Governor Carolyn Rogers used a speech in early October to say plainly that monetary policy is too blunt an instrument to solve affordability, and for anyone building wealth through property, that admission is worth more than another quarter point cut.
Rogers made the mechanics clear. The Bank sets one rate for the entire economy. It cannot build homes, rezone land, or speed up permits. Cut the rate and more buyers qualify, but with supply still constrained, prices simply absorb the extra demand. Raise it and affordability on paper improves while fewer households can actually borrow. Either direction, the lever does not reach the root problem, which is supply. For investors, this is not a bearish signal. It is clarity. If you have been waiting for a dramatic rate drop to unlock cheaper financing and a buyer’s market at the same time, Rogers just told you that combination is unlikely to arrive.
Consider the numbers already on the board. The national average home price sat at $668,219 in August, up only 0.6 percent year over year, even as sales volume fell 6.9 percent. That is a market cooling in transaction activity while holding its price floor, a pattern that rewards patient capital over opportunistic timing. Desjardins expects the policy rate, currently held at 2.25 percent, to stay flat through year end before rising half a point in the first half of 2027. That is not the setup for a rush of cheap leverage. It is a setup for disciplined underwriting.
The renewal wave deserves particular attention from anyone holding leveraged property. Roughly 12 percent of outstanding Canadian mortgages, the last cohort of pandemic-era five-year fixed terms, will renew over the next year. The Bank’s own Financial Stability Report projects payments on these loans rising about 15 percent on average, meaning a $2,000 monthly payment could climb toward $2,300. That is a real cash flow event for landlords and owner-investors alike, and it should be modeled now, not discovered at the renewal letter. There is a workaround worth knowing: OSFI does not expect lenders to apply the stress test to uninsured borrowers who switch lenders at renewal without increasing their loan amount, which opens genuine room to shop rates rather than accept a renewal offer passively.
Rising prices made housing less affordable, but they also supported household wealth and economic growth.
That tension, between affordability and the household wealth built into home equity, is the real investment signal here. Rogers herself warned that falling prices would reduce household wealth and stress borrowers and lenders, which tells you the Bank has little appetite for engineering a price correction. For investors, that reads as a floor under values even amid soft sales. The strategy that follows is not about predicting the next rate decision on October 28. It is about underwriting deals at today’s stress-test rate, stress testing your own renewals against a 15 percent payment increase, and recognizing that in a market where policy cannot move the real constraint, supply and location fundamentals matter more than ever.
Source: Yahoo Finance / Money.ca
Rate Cuts Won’t Save Affordability: What the BoC’s Blunt-Tool Admission Means for Your Property Strategy
When the second most powerful voice at the Bank of Canada tells you not to count on interest rates to fix housing, you listen, and more importantly, you reposition. Senior Deputy Governor Carolyn Rogers used a speech in early October to say plainly that monetary policy is too blunt an instrument to solve affordability, and for anyone building wealth through property, that admission is worth more than another quarter point cut.
Rogers made the mechanics clear. The Bank sets one rate for the entire economy. It cannot build homes, rezone land, or speed up permits. Cut the rate and more buyers qualify, but with supply still constrained, prices simply absorb the extra demand. Raise it and affordability on paper improves while fewer households can actually borrow. Either direction, the lever does not reach the root problem, which is supply. For investors, this is not a bearish signal. It is clarity. If you have been waiting for a dramatic rate drop to unlock cheaper financing and a buyer’s market at the same time, Rogers just told you that combination is unlikely to arrive.
Consider the numbers already on the board. The national average home price sat at $668,219 in August, up only 0.6 percent year over year, even as sales volume fell 6.9 percent. That is a market cooling in transaction activity while holding its price floor, a pattern that rewards patient capital over opportunistic timing. Desjardins expects the policy rate, currently held at 2.25 percent, to stay flat through year end before rising half a point in the first half of 2027. That is not the setup for a rush of cheap leverage. It is a setup for disciplined underwriting.
The renewal wave deserves particular attention from anyone holding leveraged property. Roughly 12 percent of outstanding Canadian mortgages, the last cohort of pandemic-era five-year fixed terms, will renew over the next year. The Bank’s own Financial Stability Report projects payments on these loans rising about 15 percent on average, meaning a $2,000 monthly payment could climb toward $2,300. That is a real cash flow event for landlords and owner-investors alike, and it should be modeled now, not discovered at the renewal letter. There is a workaround worth knowing: OSFI does not expect lenders to apply the stress test to uninsured borrowers who switch lenders at renewal without increasing their loan amount, which opens genuine room to shop rates rather than accept a renewal offer passively.
Rising prices made housing less affordable, but they also supported household wealth and economic growth.
That tension, between affordability and the household wealth built into home equity, is the real investment signal here. Rogers herself warned that falling prices would reduce household wealth and stress borrowers and lenders, which tells you the Bank has little appetite for engineering a price correction. For investors, that reads as a floor under values even amid soft sales. The strategy that follows is not about predicting the next rate decision on October 28. It is about underwriting deals at today’s stress-test rate, stress testing your own renewals against a 15 percent payment increase, and recognizing that in a market where policy cannot move the real constraint, supply and location fundamentals matter more than ever.
Source: Yahoo Finance / Money.ca
Rate Cuts Won’t Save Affordability: What the BoC’s Blunt-Tool Admission Means for Your Property Strategy
When the second most powerful voice at the Bank of Canada tells you not to count on interest rates to fix housing, you listen, and more importantly, you reposition. Senior Deputy Governor Carolyn Rogers used a speech in early October to say plainly that monetary policy is too blunt an instrument to solve affordability, and for anyone building wealth through property, that admission is worth more than another quarter point cut.
Rogers made the mechanics clear. The Bank sets one rate for the entire economy. It cannot build homes, rezone land, or speed up permits. Cut the rate and more buyers qualify, but with supply still constrained, prices simply absorb the extra demand. Raise it and affordability on paper improves while fewer households can actually borrow. Either direction, the lever does not reach the root problem, which is supply. For investors, this is not a bearish signal. It is clarity. If you have been waiting for a dramatic rate drop to unlock cheaper financing and a buyer’s market at the same time, Rogers just told you that combination is unlikely to arrive.
Consider the numbers already on the board. The national average home price sat at $668,219 in August, up only 0.6 percent year over year, even as sales volume fell 6.9 percent. That is a market cooling in transaction activity while holding its price floor, a pattern that rewards patient capital over opportunistic timing. Desjardins expects the policy rate, currently held at 2.25 percent, to stay flat through year end before rising half a point in the first half of 2027. That is not the setup for a rush of cheap leverage. It is a setup for disciplined underwriting.
The renewal wave deserves particular attention from anyone holding leveraged property. Roughly 12 percent of outstanding Canadian mortgages, the last cohort of pandemic-era five-year fixed terms, will renew over the next year. The Bank’s own Financial Stability Report projects payments on these loans rising about 15 percent on average, meaning a $2,000 monthly payment could climb toward $2,300. That is a real cash flow event for landlords and owner-investors alike, and it should be modeled now, not discovered at the renewal letter. There is a workaround worth knowing: OSFI does not expect lenders to apply the stress test to uninsured borrowers who switch lenders at renewal without increasing their loan amount, which opens genuine room to shop rates rather than accept a renewal offer passively.
Rising prices made housing less affordable, but they also supported household wealth and economic growth.
That tension, between affordability and the household wealth built into home equity, is the real investment signal here. Rogers herself warned that falling prices would reduce household wealth and stress borrowers and lenders, which tells you the Bank has little appetite for engineering a price correction. For investors, that reads as a floor under values even amid soft sales. The strategy that follows is not about predicting the next rate decision on October 28. It is about underwriting deals at today’s stress-test rate, stress testing your own renewals against a 15 percent payment increase, and recognizing that in a market where policy cannot move the real constraint, supply and location fundamentals matter more than ever.
Source: Yahoo Finance / Money.ca
Rate Cuts Won’t Save Affordability: What the BoC’s Blunt-Tool Admission Means for Your Property Strategy
When the second most powerful voice at the Bank of Canada tells you not to count on interest rates to fix housing, you listen, and more importantly, you reposition. Senior Deputy Governor Carolyn Rogers used a speech in early October to say plainly that monetary policy is too blunt an instrument to solve affordability, and for anyone building wealth through property, that admission is worth more than another quarter point cut.
Rogers made the mechanics clear. The Bank sets one rate for the entire economy. It cannot build homes, rezone land, or speed up permits. Cut the rate and more buyers qualify, but with supply still constrained, prices simply absorb the extra demand. Raise it and affordability on paper improves while fewer households can actually borrow. Either direction, the lever does not reach the root problem, which is supply. For investors, this is not a bearish signal. It is clarity. If you have been waiting for a dramatic rate drop to unlock cheaper financing and a buyer’s market at the same time, Rogers just told you that combination is unlikely to arrive.
Consider the numbers already on the board. The national average home price sat at $668,219 in August, up only 0.6 percent year over year, even as sales volume fell 6.9 percent. That is a market cooling in transaction activity while holding its price floor, a pattern that rewards patient capital over opportunistic timing. Desjardins expects the policy rate, currently held at 2.25 percent, to stay flat through year end before rising half a point in the first half of 2027. That is not the setup for a rush of cheap leverage. It is a setup for disciplined underwriting.
The renewal wave deserves particular attention from anyone holding leveraged property. Roughly 12 percent of outstanding Canadian mortgages, the last cohort of pandemic-era five-year fixed terms, will renew over the next year. The Bank’s own Financial Stability Report projects payments on these loans rising about 15 percent on average, meaning a $2,000 monthly payment could climb toward $2,300. That is a real cash flow event for landlords and owner-investors alike, and it should be modeled now, not discovered at the renewal letter. There is a workaround worth knowing: OSFI does not expect lenders to apply the stress test to uninsured borrowers who switch lenders at renewal without increasing their loan amount, which opens genuine room to shop rates rather than accept a renewal offer passively.
Rising prices made housing less affordable, but they also supported household wealth and economic growth.
That tension, between affordability and the household wealth built into home equity, is the real investment signal here. Rogers herself warned that falling prices would reduce household wealth and stress borrowers and lenders, which tells you the Bank has little appetite for engineering a price correction. For investors, that reads as a floor under values even amid soft sales. The strategy that follows is not about predicting the next rate decision on October 28. It is about underwriting deals at today’s stress-test rate, stress testing your own renewals against a 15 percent payment increase, and recognizing that in a market where policy cannot move the real constraint, supply and location fundamentals matter more than ever.
Source: Yahoo Finance / Money.ca
When the second most powerful voice at the Bank of Canada tells you not to count on interest rates to fix housing, you listen, and more importantly, you reposition. Senior Deputy Governor Carolyn Rogers used a speech in early October to say plainly that monetary policy is too blunt an instrument to solve affordability, and for anyone building wealth through property, that admission is worth more than another quarter point cut.
Rogers made the mechanics clear. The Bank sets one rate for the entire economy. It cannot build homes, rezone land, or speed up permits. Cut the rate and more buyers qualify, but with supply still constrained, prices simply absorb the extra demand. Raise it and affordability on paper improves while fewer households can actually borrow. Either direction, the lever does not reach the root problem, which is supply. For investors, this is not a bearish signal. It is clarity. If you have been waiting for a dramatic rate drop to unlock cheaper financing and a buyer’s market at the same time, Rogers just told you that combination is unlikely to arrive.
Consider the numbers already on the board. The national average home price sat at $668,219 in August, up only 0.6 percent year over year, even as sales volume fell 6.9 percent. That is a market cooling in transaction activity while holding its price floor, a pattern that rewards patient capital over opportunistic timing. Desjardins expects the policy rate, currently held at 2.25 percent, to stay flat through year end before rising half a point in the first half of 2027. That is not the setup for a rush of cheap leverage. It is a setup for disciplined underwriting.
The renewal wave deserves particular attention from anyone holding leveraged property. Roughly 12 percent of outstanding Canadian mortgages, the last cohort of pandemic-era five-year fixed terms, will renew over the next year. The Bank’s own Financial Stability Report projects payments on these loans rising about 15 percent on average, meaning a $2,000 monthly payment could climb toward $2,300. That is a real cash flow event for landlords and owner-investors alike, and it should be modeled now, not discovered at the renewal letter. There is a workaround worth knowing: OSFI does not expect lenders to apply the stress test to uninsured borrowers who switch lenders at renewal without increasing their loan amount, which opens genuine room to shop rates rather than accept a renewal offer passively.
Rising prices made housing less affordable, but they also supported household wealth and economic growth.
That tension, between affordability and the household wealth built into home equity, is the real investment signal here. Rogers herself warned that falling prices would reduce household wealth and stress borrowers and lenders, which tells you the Bank has little appetite for engineering a price correction. For investors, that reads as a floor under values even amid soft sales. The strategy that follows is not about predicting the next rate decision on October 28. It is about underwriting deals at today’s stress-test rate, stress testing your own renewals against a 15 percent payment increase, and recognizing that in a market where policy cannot move the real constraint, supply and location fundamentals matter more than ever.
Source: Yahoo Finance / Money.ca
Rate Cuts Won’t Save Affordability: What the BoC’s Blunt-Tool Admission Means for Your Property Strategy
When the second most powerful voice at the Bank of Canada tells you not to count on interest rates to fix housing, you listen, and more importantly, you reposition. Senior Deputy Governor Carolyn Rogers used a speech in early October to say plainly that monetary policy is too blunt an instrument to solve affordability, and for anyone building wealth through property, that admission is worth more than another quarter point cut.
Rogers made the mechanics clear. The Bank sets one rate for the entire economy. It cannot build homes, rezone land, or speed up permits. Cut the rate and more buyers qualify, but with supply still constrained, prices simply absorb the extra demand. Raise it and affordability on paper improves while fewer households can actually borrow. Either direction, the lever does not reach the root problem, which is supply. For investors, this is not a bearish signal. It is clarity. If you have been waiting for a dramatic rate drop to unlock cheaper financing and a buyer’s market at the same time, Rogers just told you that combination is unlikely to arrive.
Consider the numbers already on the board. The national average home price sat at $668,219 in August, up only 0.6 percent year over year, even as sales volume fell 6.9 percent. That is a market cooling in transaction activity while holding its price floor, a pattern that rewards patient capital over opportunistic timing. Desjardins expects the policy rate, currently held at 2.25 percent, to stay flat through year end before rising half a point in the first half of 2027. That is not the setup for a rush of cheap leverage. It is a setup for disciplined underwriting.
The renewal wave deserves particular attention from anyone holding leveraged property. Roughly 12 percent of outstanding Canadian mortgages, the last cohort of pandemic-era five-year fixed terms, will renew over the next year. The Bank’s own Financial Stability Report projects payments on these loans rising about 15 percent on average, meaning a $2,000 monthly payment could climb toward $2,300. That is a real cash flow event for landlords and owner-investors alike, and it should be modeled now, not discovered at the renewal letter. There is a workaround worth knowing: OSFI does not expect lenders to apply the stress test to uninsured borrowers who switch lenders at renewal without increasing their loan amount, which opens genuine room to shop rates rather than accept a renewal offer passively.
Rising prices made housing less affordable, but they also supported household wealth and economic growth.
That tension, between affordability and the household wealth built into home equity, is the real investment signal here. Rogers herself warned that falling prices would reduce household wealth and stress borrowers and lenders, which tells you the Bank has little appetite for engineering a price correction. For investors, that reads as a floor under values even amid soft sales. The strategy that follows is not about predicting the next rate decision on October 28. It is about underwriting deals at today’s stress-test rate, stress testing your own renewals against a 15 percent payment increase, and recognizing that in a market where policy cannot move the real constraint, supply and location fundamentals matter more than ever.
Source: Yahoo Finance / Money.ca
Rate Cuts Won’t Save Affordability: What the BoC’s Blunt-Tool Admission Means for Your Property Strategy
When the second most powerful voice at the Bank of Canada tells you not to count on interest rates to fix housing, you listen, and more importantly, you reposition. Senior Deputy Governor Carolyn Rogers used a speech in early October to say plainly that monetary policy is too blunt an instrument to solve affordability, and for anyone building wealth through property, that admission is worth more than another quarter point cut.
Rogers made the mechanics clear. The Bank sets one rate for the entire economy. It cannot build homes, rezone land, or speed up permits. Cut the rate and more buyers qualify, but with supply still constrained, prices simply absorb the extra demand. Raise it and affordability on paper improves while fewer households can actually borrow. Either direction, the lever does not reach the root problem, which is supply. For investors, this is not a bearish signal. It is clarity. If you have been waiting for a dramatic rate drop to unlock cheaper financing and a buyer’s market at the same time, Rogers just told you that combination is unlikely to arrive.
Consider the numbers already on the board. The national average home price sat at $668,219 in August, up only 0.6 percent year over year, even as sales volume fell 6.9 percent. That is a market cooling in transaction activity while holding its price floor, a pattern that rewards patient capital over opportunistic timing. Desjardins expects the policy rate, currently held at 2.25 percent, to stay flat through year end before rising half a point in the first half of 2027. That is not the setup for a rush of cheap leverage. It is a setup for disciplined underwriting.
The renewal wave deserves particular attention from anyone holding leveraged property. Roughly 12 percent of outstanding Canadian mortgages, the last cohort of pandemic-era five-year fixed terms, will renew over the next year. The Bank’s own Financial Stability Report projects payments on these loans rising about 15 percent on average, meaning a $2,000 monthly payment could climb toward $2,300. That is a real cash flow event for landlords and owner-investors alike, and it should be modeled now, not discovered at the renewal letter. There is a workaround worth knowing: OSFI does not expect lenders to apply the stress test to uninsured borrowers who switch lenders at renewal without increasing their loan amount, which opens genuine room to shop rates rather than accept a renewal offer passively.
Rising prices made housing less affordable, but they also supported household wealth and economic growth.
That tension, between affordability and the household wealth built into home equity, is the real investment signal here. Rogers herself warned that falling prices would reduce household wealth and stress borrowers and lenders, which tells you the Bank has little appetite for engineering a price correction. For investors, that reads as a floor under values even amid soft sales. The strategy that follows is not about predicting the next rate decision on October 28. It is about underwriting deals at today’s stress-test rate, stress testing your own renewals against a 15 percent payment increase, and recognizing that in a market where policy cannot move the real constraint, supply and location fundamentals matter more than ever.
Source: Yahoo Finance / Money.ca
When the second most powerful voice at the Bank of Canada tells you not to count on interest rates to fix housing, you listen, and more importantly, you reposition. Senior Deputy Governor Carolyn Rogers used a speech in early October to say plainly that monetary policy is too blunt an instrument to solve affordability, and for anyone building wealth through property, that admission is worth more than another quarter point cut.
Rogers made the mechanics clear. The Bank sets one rate for the entire economy. It cannot build homes, rezone land, or speed up permits. Cut the rate and more buyers qualify, but with supply still constrained, prices simply absorb the extra demand. Raise it and affordability on paper improves while fewer households can actually borrow. Either direction, the lever does not reach the root problem, which is supply. For investors, this is not a bearish signal. It is clarity. If you have been waiting for a dramatic rate drop to unlock cheaper financing and a buyer’s market at the same time, Rogers just told you that combination is unlikely to arrive.
Consider the numbers already on the board. The national average home price sat at $668,219 in August, up only 0.6 percent year over year, even as sales volume fell 6.9 percent. That is a market cooling in transaction activity while holding its price floor, a pattern that rewards patient capital over opportunistic timing. Desjardins expects the policy rate, currently held at 2.25 percent, to stay flat through year end before rising half a point in the first half of 2027. That is not the setup for a rush of cheap leverage. It is a setup for disciplined underwriting.
The renewal wave deserves particular attention from anyone holding leveraged property. Roughly 12 percent of outstanding Canadian mortgages, the last cohort of pandemic-era five-year fixed terms, will renew over the next year. The Bank’s own Financial Stability Report projects payments on these loans rising about 15 percent on average, meaning a $2,000 monthly payment could climb toward $2,300. That is a real cash flow event for landlords and owner-investors alike, and it should be modeled now, not discovered at the renewal letter. There is a workaround worth knowing: OSFI does not expect lenders to apply the stress test to uninsured borrowers who switch lenders at renewal without increasing their loan amount, which opens genuine room to shop rates rather than accept a renewal offer passively.
Rising prices made housing less affordable, but they also supported household wealth and economic growth.
That tension, between affordability and the household wealth built into home equity, is the real investment signal here. Rogers herself warned that falling prices would reduce household wealth and stress borrowers and lenders, which tells you the Bank has little appetite for engineering a price correction. For investors, that reads as a floor under values even amid soft sales. The strategy that follows is not about predicting the next rate decision on October 28. It is about underwriting deals at today’s stress-test rate, stress testing your own renewals against a 15 percent payment increase, and recognizing that in a market where policy cannot move the real constraint, supply and location fundamentals matter more than ever.
Source: Yahoo Finance / Money.ca
Rate Cuts Won’t Save Affordability: What the BoC’s Blunt-Tool Admission Means for Your Property Strategy
When the second most powerful voice at the Bank of Canada tells you not to count on interest rates to fix housing, you listen, and more importantly, you reposition. Senior Deputy Governor Carolyn Rogers used a speech in early October to say plainly that monetary policy is too blunt an instrument to solve affordability, and for anyone building wealth through property, that admission is worth more than another quarter point cut.
Rogers made the mechanics clear. The Bank sets one rate for the entire economy. It cannot build homes, rezone land, or speed up permits. Cut the rate and more buyers qualify, but with supply still constrained, prices simply absorb the extra demand. Raise it and affordability on paper improves while fewer households can actually borrow. Either direction, the lever does not reach the root problem, which is supply. For investors, this is not a bearish signal. It is clarity. If you have been waiting for a dramatic rate drop to unlock cheaper financing and a buyer’s market at the same time, Rogers just told you that combination is unlikely to arrive.
Consider the numbers already on the board. The national average home price sat at $668,219 in August, up only 0.6 percent year over year, even as sales volume fell 6.9 percent. That is a market cooling in transaction activity while holding its price floor, a pattern that rewards patient capital over opportunistic timing. Desjardins expects the policy rate, currently held at 2.25 percent, to stay flat through year end before rising half a point in the first half of 2027. That is not the setup for a rush of cheap leverage. It is a setup for disciplined underwriting.
The renewal wave deserves particular attention from anyone holding leveraged property. Roughly 12 percent of outstanding Canadian mortgages, the last cohort of pandemic-era five-year fixed terms, will renew over the next year. The Bank’s own Financial Stability Report projects payments on these loans rising about 15 percent on average, meaning a $2,000 monthly payment could climb toward $2,300. That is a real cash flow event for landlords and owner-investors alike, and it should be modeled now, not discovered at the renewal letter. There is a workaround worth knowing: OSFI does not expect lenders to apply the stress test to uninsured borrowers who switch lenders at renewal without increasing their loan amount, which opens genuine room to shop rates rather than accept a renewal offer passively.
Rising prices made housing less affordable, but they also supported household wealth and economic growth.
That tension, between affordability and the household wealth built into home equity, is the real investment signal here. Rogers herself warned that falling prices would reduce household wealth and stress borrowers and lenders, which tells you the Bank has little appetite for engineering a price correction. For investors, that reads as a floor under values even amid soft sales. The strategy that follows is not about predicting the next rate decision on October 28. It is about underwriting deals at today’s stress-test rate, stress testing your own renewals against a 15 percent payment increase, and recognizing that in a market where policy cannot move the real constraint, supply and location fundamentals matter more than ever.
Source: Yahoo Finance / Money.ca