Ottawa’s New Home Carve-Out: What the Foreign Buyer Exemption Means for Investors
Policy shifts rarely arrive without a story attached, and Canada’s latest move is no exception. Budget 2026 extends the ban on foreign purchases of existing homes to January 1, 2029, while quietly carving out an exemption for new residential properties. For readers tracking capital flows into Canadian housing, this is not a footnote. It is a signal worth reading carefully before anyone repositions a portfolio around it.
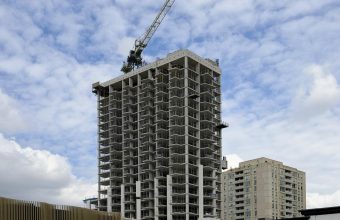
The timing tells its own story. New home sales in major markets like Toronto are sitting near record lows, developers are carrying historic levels of unsold inventory, and taxpayers have already backstopped billions in condo developer bailouts in Ontario. Against that backdrop, opening new construction to foreign capital reads less like an affordability measure and more like a demand-side rescue for a segment of the market that has struggled to clear.
For investors, the critical question is not whether this policy sounds good on paper, it is whether the capital it is designed to attract actually shows up. Property records from 2019 and 2020 show foreign ownership was concentrated precisely in new builds, with non-resident buyers holding double-digit shares of new condo stock in Vancouver, British Columbia overall, and several other provinces. That historical demand was driven overwhelmingly by Chinese capital, which previously accounted for roughly 70 percent of non-resident buying activity in Canadian housing.
That source of demand has since cooled considerably. Beijing has tightened outbound capital controls and continues to encourage its wealthiest citizens to repatriate overseas assets, while Canada’s reputation as a politically neutral safe haven for capital has eroded. International student flows from China, once Canada’s largest source, have also fallen sharply. The conditions that built Vancouver’s and Toronto’s foreign buying booms in the last decade are not simply available to be switched back on.
The strongest real estate opportunities are rarely found by looking at policy headlines alone. They come from understanding where demand is actually capable of showing up.
What this likely means in practice is a smaller, different pool of foreign capital than before, potentially from new source markets, possibly drawn in through discounted pricing on new inventory sold overseas, a practice already used to move unsold units without disturbing domestic price benchmarks. For investors holding completed or near-completed new construction assets, any incremental foreign demand is a modest tailwind on absorption. For those evaluating new acquisitions, the more important variable remains unchanged: elevated supply, weak domestic affordability, and a construction pipeline still running well above the 2015-2019 average.
This is a policy to watch rather than react to. The exemption may ease some developer pressure in oversupplied segments, but it does not resolve the underlying affordability gap driving weak domestic demand, and it should not be mistaken for a structural return of the capital flows that shaped the last foreign buying cycle. Investors should treat this as one input among many, not a thesis on its own.
Source: Better Dwelling, “Canada To Lift Ban On Foreign Buyers of New Homes For ‘Affordability'”